Real Estate
How to Build a UK Property Portfolio Step-by-Step Guide

Building a UK property portfolio can be a rewarding venture. It offers the potential for financial growth and stability. However, it requires careful planning and strategic execution.
The UK property market is dynamic and ever-changing. Understanding its nuances is crucial for success. This guide will walk you through the process step-by-step.
Setting clear investment goals is the first step. Knowing what you want to achieve helps shape your strategy. It also guides your decision-making process.
Assessing your financial position is equally important. It determines the scale of your investment. It also influences the types of properties you can consider.
Choosing the right investment strategy is key. Whether it’s buy-to-let or flipping, each has its pros and cons. Your choice should align with your goals and risk tolerance.
Conducting thorough market research is essential. It helps identify lucrative opportunities.
It also minimises the risk of poor investment decisions.
Securing financing is another critical step. Understanding mortgage options and securing favourable terms can significantly impact your returns.
Finally, managing your properties effectively ensures long-term success. It involves maintaining the properties and managing tenant relationships. This guide will cover all these aspects and more.
Understanding the UK Property Market
The UK property market is an intricate ecosystem. It is influenced by multiple factors including economic conditions and government policies. Keeping abreast of these changes is vital for investors.
Economic conditions such as inflation and interest rates impact property values. They can affect both the affordability and attractiveness of properties. Being informed helps you make sound decisions.
Government policies, like tax laws and housing regulations, can also play a significant role. These policies can either encourage or discourage property investment. Staying updated ensures compliance and maximises opportunities.
Location holds significant importance in property investment. Different regions offer varied growth prospects and rental yields. A well-chosen location can significantly boost your investment returns.
Understanding demographic trends is also beneficial. The needs and preferences of different age groups can affect demand. Knowing your target market allows you to tailor your investment strategy effectively.
Here’s a brief overview of key factors to consider in the UK property market:
- Economic trends (e.g., interest rates, inflation)
- Government policies (e.g., taxation, housing regulations)
- Location and regional development
- Demographic trends (e.g., ageing population, young professionals)
Market research is crucial for identifying emerging trends. New developments or transport links can raise property values significantly. Early identification of such opportunities can give you a competitive edge.
Gaining insights into tenant preferences can also be beneficial. This helps tailor properties to meet market demand, potentially maximising returns. Understanding the UK property market’s complexities is essential for crafting a resilient investment strategy.
Setting Your Investment Goals and Strategy
Setting clear investment goals is your roadmap to success. Start by asking yourself what you hope to achieve with your property portfolio. Whether it’s generating income or long-term capital growth, clarity is key.
Your investment strategy should align with your goals. Are you aiming for steady rental income or hoping for capital appreciation? Each goal requires a different approach and focus.
Risk tolerance is another critical factor. Understand your comfort level with market volatility. Higher returns often come with increased risk, so balance is essential.
Consider your investment timeline. Output (British English):
Are you looking for short-term gains or planning for retirement? Your timeline will influence your property type and location decisions.
Creating a strategic plan involves several components:
- Defining clear, measurable goals
- Understanding your risk tolerance
- Deciding on your investment timeline
- Choosing a suitable property investment strategy
Assessing your financial resources is also crucial. This includes your available capital and your borrowing capacity. Knowing these limits helps avoid overstretching your finances.
Continually review and adjust your strategy. As market conditions and personal circumstances change, adaptability ensures ongoing success. A well-defined strategy provides direction and helps in making informed decisions.
Assessing Your Financial Position and Risk Profile
Before diving into property investment, assess your financial health. Understanding this helps set realistic expectations and prevents overextension.
Evaluate your assets, liabilities, and cash flow to get a clear financial picture.
Create a detailed budget to identify disposable income for investments. Consider all potential expenses, such as mortgage payments and property maintenance. This foresight is crucial in managing your investment smoothly.
Determining your risk profile is equally important. Are you a risk-taker or do you prefer a safer approach? This will guide your investment choices, influencing the properties you choose and how you manage them.
By analysing both your financial position and your risk profile, you can create a tailored investment plan:
- Evaluate income versus expenses
- Determine available investment capital
- Identify any existing liabilities
- Understand your investment risk tolerance
Knowing your borrowing capacity is vital. Speak with lenders or mortgage brokers to understand what you can borrow. This awareness ensures that you make informed decisions when purchasing properties.
Finally, be prepared for unexpected changes in your financial situation. Flexibility in your approach allows for adjustments without straying from your investment goals. Adaptability is often the difference between success and setbacks in property investment.
Choosing the Right Property Investment Strategy
Selecting the right investment strategy is crucial for building a successful UK property portfolio. Each strategy has its own risks and benefits, shaping the investment journey. Understanding these can help maximise returns and avoid pitfalls.
Start by exploring different types of property investments available. The three most common strategies include buy-to-let, flipping, and commercial properties. Each requires a unique approach and offers distinct rewards.
- Buy-to-Let: Buying a property to rent out to tenants.
- Flipping: Purchasing properties to renovate and sell for a profit.
Commercial Properties: Investing in office spaces, retail outlets, or industrial units.
Consider your personal goals and risk appetite. If seeking steady cash flow, buy-to-let properties offer consistent rental income. For quicker capital gains, flipping might be suitable, provided you understand the renovation process and market conditions.
Choose a strategy aligned with the capital you have. Flipping might require higher upfront costs, while buy-to-let could be more capital-efficient with mortgage financing. Commercial properties can demand the most capital but may offer higher returns.
- Low Capital: Buy-to-let with a mortgage.
- Medium Capital: Flipping with partial financing.
- High Capital: Commercial investments with or without financing.
The local market conditions also play a role. Research areas with high demand and limited supply for rental properties.
Areas undergoing regeneration can offer growth opportunities for both residential and commercial investments.
Blend different strategies to diversify and mitigate risk. A mix of residential and commercial properties, for instance, can provide both steady income and potential high returns. Finally, remain flexible. As market conditions change, so too might your ideal investment strategy. Continuously educate yourself and adjust your approach as needed.
Conducting Market Research and Property Analysis
Thorough market research is essential for successful property investment in the UK. Understanding market dynamics helps identify profitable opportunities and minimise risks. Start by analysing current trends and future forecasts.
Begin by identifying potential locations. Consider factors such as economic growth, employment rates, and population trends. High-growth areas often promise better returns.
Access to transport links and local amenities can also impact property values significantly.
Next, dive into specific property characteristics. Focus on property types and sizes that are in high demand. A three-bedroom house in a family-oriented neighbourhood may be more appealing than a studio flat in the same area.
Understand the local rental market. Check average rental yields and compare them with surrounding areas. Yield is a key measure of an investment’s viability and helps gauge return potential.
Create a checklist for property analysis to ensure comprehensive evaluation:
- Location and Accessibility: Proximity to transport and amenities.
- Market Demand: Popular property types and tenant preferences.
- Economic Indicators: Local employment and population growth.
- Rental Yields: Average rates and projected increases.
- Property Condition: Needed repairs or renovations.
Additionally, conduct competitor analysis. Observe other investors’ strategies in your target area. Assess the types of properties they invest in and their pricing tactics. Learning from others can offer invaluable insights.
Regularly review market conditions. What works today might not in the future. Stay informed about emerging trends, such as sustainable and eco-friendly properties, which could influence future demand and investment success.
Financing Your Property Portfolio
Financing your property portfolio is a crucial step in building a successful investment strategy. Understanding your options and securing the right finance can greatly impact your long-term returns.
Begin by determining how much you can afford to borrow. This depends on your income, expenses, and current financial obligations. A detailed budget will help clarify your borrowing capacity.
Explore different mortgage options available to property investors. Each has unique terms and benefits. Popular choices include buy-to-let mortgages and commercial property loans. Consult with a mortgage broker for personalised advice.
It’s also essential to understand the terms and conditions of each financing option. Factors such as interest rates, fees, and repayment schedules can influence your decision. Shorter loan terms may lead to higher monthly payments but lower overall interest costs.
Consider the advantages of leveraging existing equity. If you own property, you might release equity to fund further investments. This can be a cost-effective way to expand your portfolio.
Create a financing strategy checklist:
- Determine Budget: Assess borrowing capacity based on income and expenses.
- Mortgage Options: Evaluate buy-to-let versus commercial loans.
- Interest Rates: Compare fixed and variable rates.
- Repayment Terms: Understand monthly payments and loan duration.
- Equity Release: Leverage existing assets for new purchases.
Finally, always work with qualified professionals. Solicitors and financial advisers ensure you understand all legal and financial implications. They help identify the best financing pathways, making your property investment journey smoother and more successful.
Legal Considerations and Compliance
Navigating the legal landscape of UK property investment is vital. Understanding regulations helps prevent costly mistakes and legal issues.
First, familiarise yourself with property ownership laws. This includes knowing about leasehold versus freehold arrangements. Each has distinct rights and responsibilities affecting your investment.
Compliance with landlord regulations is also critical. Safety standards, tenant rights, and eviction protocols require attention. Non-compliance can lead to fines or disputes, affecting your reputation and finances.
Tax implications should not be overlooked. Stamp duty, capital gains tax, and income tax impact profitability. Consult a tax adviser to ensure your tax strategy is optimised.
Create a basic legal checklist:
- Ownership: Understand leasehold versus freehold.
- Landlord Regulations: Comply with safety, tenant, and eviction laws.
- Tax Compliance: Monitor property-related taxes.
Finally, always seek professional legal counsel. Solicitors specialising in property law guide you through complex transactions. They help protect your investments by ensuring all legal aspects are in order. Taking these steps ensures a legally compliant and secure investment portfolio.
Structuring Your Property Portfolio
Structuring a property portfolio requires a strategic approach. Decide on the investment mix that aligns with your goals and risk tolerance. A well-structured portfolio balances different property types and locations.
Start by identifying core properties. These are stable, income-generating assets that provide consistent returns. Core properties often serve as the portfolio’s foundation.
Next, consider adding value-add properties. These require improvements or management changes to enhance value. They might offer higher returns but involve more risk and active involvement.
Diversification is key to a resilient portfolio. Spreading investments across different regions or sectors reduces risk. It safeguards against market fluctuations.
Here’s a quick checklist for structuring:
- Identify Core Properties: Focus on stability and income.
- Explore Value-Add Opportunities: Aim for higher returns with improvements.
- Diversify: Vary property types and locations.
Finally, regularly review your portfolio’s structure. Economic changes or personal circumstances might necessitate adjustments. Adaptive strategies ensure continued alignment with investment objectives.
Achieving a well-structured portfolio involves both planning and flexibility.
Selecting and Acquiring Your First Property
Selecting your first property is an exciting step. It sets the foundation for your entire portfolio. This initial choice requires careful consideration.
Begin by establishing your budget. Know your financial limits and potential funding sources. This clarity narrows your search and avoids overspending.
Location is crucial. Analyse areas with strong rental demand or growth potential. Consider proximity to amenities and transport links, which attract tenants and boost property value.
Next, evaluate the property’s condition. Factor in renovation costs if significant improvements are needed. A thorough inspection can save future headaches and financial surprises.
Here’s a checklist for selecting and acquiring your property:
- Set a Budget: Know your financial range.
- Choose the Right Location: Evaluate tenant demand and growth potential.
- Inspect Thoroughly: Assess the condition and renovation needs.
Now, prepare for negotiations. Understand the market value to make competitive offers without overpaying. Negotiation skills are vital for securing the best price.
Once acquired, manage the transition smoothly. Have a plan for any necessary updates before letting. Efficient management can attract quality tenants quickly, ensuring your property starts generating income without delay.
Managing Your Property and Tenants
Effective property management is key to a successful portfolio. It ensures consistent rental income and preserves property value. This role often requires juggling multiple responsibilities.
Begin with setting clear tenancy agreements. These documents outline obligations for both parties, reducing disputes. Clarity at the start sets the tone for positive relations.
Regular property maintenance is crucial. Routine checks and timely repairs prevent issues from escalating. This proactive approach protects your investment and keeps tenants happy.
Good communication with tenants is essential. Being responsive to enquiries and problems fosters trust and satisfaction. Happy tenants are more likely to renew tenancies, reducing vacancy rates.
Consider employing a property manager if time is limited. Professionals can efficiently handle day-to-day operations. They offer expertise and peace of mind, freeing you to focus on growing your portfolio.
Here’s a quick guide to managing your properties:
- Create Clear Agreements: Outline responsibilities to prevent misunderstandings.
- Maintain Regularly: Conduct routine checks to preserve property conditions.
- Communicate Effectively: Foster trust with prompt responses.
- Consider Professional Management: Delegate tasks to professionals if needed.
By focusing on these areas, you enhance tenant retention and property performance. This approach not only safeguards your investment but also supports the long-term growth of your property portfolio.
Calculating Returns: Rental Yield and Capital Growth
Understanding returns is crucial in property investment. It guides decisions and measures success. Two key metrics to consider are rental yield and capital growth.
Rental yield indicates annual income potential. It’s calculated by dividing annual rent by the property’s value. A higher yield suggests a better income source.
Capital growth refers to the increase in property value over time. It’s influenced by market conditions, property improvements, and the desirability of the location. High growth rates usually imply a profitable investment.
To effectively evaluate these metrics, follow these steps:
- Determine Annual Rent: Factor in rent per week or month multiplied over a year.
- Assess Property Value: Use current market valuations.
- Calculate Rental Yield: Divide annual rent by property value, then multiply by 100.
- Track Capital Growth: Compare the property’s past and present valuations.
Balancing these returns can boost portfolio success. Prioritise properties offering both stable rental yield and good prospects for capital growth. This balanced approach enhances long-term financial gains and helps in building a sustainable property portfolio.
Diversifying and Scaling Your Portfolio
Diversifying your property portfolio spreads risk. It allows you to capitalise on different market segments. This approach can strengthen financial stability.
Start by mixing property types. Include residential, commercial, and mixed-use properties. Such diversity mitigates market fluctuations in specific sectors.
Additionally, explore various geographic locations. Invest in both urban and suburban areas. This broadens exposure to differing economic and demographic trends.
Scaling your portfolio gradually is key to sustainable growth. Don’t rush purchases; instead, assess each opportunity with care. Evaluate potential returns, risks, and market conditions.
To successfully diversify and scale, consider the following strategies:
- Geographic Expansion: Buy properties in varied regions.
- Different Property Types: Mix residential and commercial investments.
- Diversified Renters: Target various tenant demographics.
Leveraging existing assets can also support growth. Use equity from current properties to fund new acquisitions. This strategy allows for expansion without extensive new financing.
Finally, stay informed about market trends and changes. Continuous education and research are vital. They help identify new opportunities and navigate challenges, ensuring growth and diversification in your UK property portfolio.
Portfolio Maintenance and Ongoing Management
Proper maintenance is crucial to preserving property value. Routine inspections and repairs are essential. These actions prevent minor issues from becoming costly problems.
Tenant satisfaction plays a significant role in successful property management. Happy tenants are more likely to renew leases. This reduces vacancy rates and ensures steady rental income.
Effective financial management is another cornerstone. Carefully track income and expenses. Consider using property management software to streamline this process.
Implementing a systematic approach to portfolio maintenance includes:
- Regular Inspections: Schedule routine property checks.
- Timely Repairs: Address maintenance issues promptly.
- Tenant Communication: Maintain open dialogue with tenants.
Additionally, keeping up with market trends is key. Stay informed about new regulations and industry changes. This knowledge helps in making timely decisions and maintaining compliance.
Overall, a proactive strategy in managing your portfolio enhances its longevity. It also boosts profitability and minimises unforeseen setbacks, supporting sustained success in UK property investment.
Taxation and Asset Protection
Navigating the UK tax system is crucial for property investors. Understanding tax obligations can save money and ensure compliance. Taxes affect your overall return on investment significantly.
Property investors should pay attention to stamp duty and capital gains tax. These taxes can impact your profitability if not planned for appropriately. Consulting a tax professional is often a wise decision.
Asset protection is another critical aspect. Protect your properties from potential claims and liabilities. Insurance is a key component in shielding your investments from unforeseen risks.
Consider these strategies for effective taxation and asset protection:
- Utilise Tax Breaks: Take advantage of relief and exemptions.
- Maintain Adequate Insurance: Protect against damage and liability.
- Seek Professional Advice: Consult with tax advisers and legal experts.
Effective management of these elements ensures your investments are safeguarded. This proactive approach supports long-term sustainability, allowing you to focus on growing your property portfolio with greater confidence.
Leveraging Technology and Professional Networks
Integrating technology into your property investment strategy is essential. Digital tools can streamline operations and offer valuable insights. These advancements simplify market research and enhance decision-making.
Technology assists with managing properties and tenants efficiently. Tools for online listings, rent collection, and maintenance requests are abundant. They provide convenience and ensure smoother management processes.
Building a strong network of professionals boosts your investment success. Collaborate with solicitors, estate agents, and property managers. Their expertise helps navigate challenges and seize opportunities in real estate.
Consider these approaches to leverage technology and networks:
- Use Property Management Software: Optimise your property operations.
- Connect with Industry Experts: Gain insights from seasoned professionals.
- Participate in Online Forums: Share experiences and gain knowledge.
By embracing both technology and professional connections, you can enhance your property portfolio. They offer invaluable support and resources that lead to more informed investment decisions. Together, they are crucial for a thriving real estate investment venture in the UK.
Common Pitfalls and How to Avoid Them
Property investment can be rewarding, yet it comes with challenges. Many investors fall into traps that hinder progress. Recognising these pitfalls early can save time and money.
One frequent mistake is neglecting proper research. Investors may buy based on emotion rather than data. This can lead to poor property selection and returns.
Another pitfall is underestimating costs.
Maintenance, taxes, and unexpected expenses add up. Failing to budget accurately affects cash flow and profitability.
To sidestep these issues, consider the following actions:
- Conduct Thorough Research: Analyse markets and trends before investing.
- Prepare for Hidden Costs: Budget wisely for unforeseen expenses.
- Seek Professional Advice: Consult experts to validate your decisions.
Avoiding these common mistakes helps safeguard your investments. By planning carefully and seeking guidance, you position yourself for long-term success in the UK property market. Investing wisely requires patience and a strategic approach, ensuring a sustainable portfolio over time.
Case Studies: Successful UK Property Investors
Learning from successful property investors can provide invaluable insights. These case studies highlight diverse strategies and outcomes.
John Smith expanded his portfolio by focusing on high-yield student accommodations.
He leveraged location advantages near universities. His steady rental income supports further investments.
Emma Johnson took a different route. She invested in upcoming urban areas with potential for appreciation. Her strategy hinged on capital growth. By renovating properties, she increased market value over time.
Sarah Brown, an investor in commercial properties, capitalised on the flourishing co-working trend. She converted old office spaces into modern co-working environments. This niche opportunity significantly boosted her rental income.
Key takeaways from these investors include:
- Identifying Niche Markets: Explore under-served segments for unique opportunities.
- Leveraging Local Growth: Invest in areas with strong economic projections.
- Adapting Strategies: Diversify to minimise risks and enhance returns.
Each of these investors pursued different paths but shared a common trait—strategic thinking. They adapted to market changes and leveraged specific opportunities for success. Their diverse strategies offer valuable lessons for aspiring property investors looking to build a robust UK portfolio.
Planning Your Exit Strategy
Crafting a clear exit plan is vital for a successful property investment journey. An exit strategy can secure profits and mitigate risks.
Decide when to exit. Timing can significantly impact returns. Monitor market trends and conditions to optimise your exit timing.
Consider different exit options:
- Selling the Property: Liquidate your asset in a favourable market.
- Refinancing: Extract equity for reinvestment while retaining ownership.
- Passing to Heirs: Transfer property to family as a legacy.
Evaluate tax implications associated with your exit plan. Ensure compliance with UK property laws. Consulting a financial adviser can help to choose the best strategy tailored to your goals and financial situation. A well-crafted exit plan ensures you can reap the rewards of your investments when the time is right.
Frequently Asked Questions
Navigating the UK property investment landscape can be complex. Many investors have common queries about building and managing a property portfolio.
Common questions include:
- How much capital do I need to start? Initial investment varies depending on location and property type.
- What are the best locations for investment? Research current market trends and potential for growth.
- How can I manage multiple properties effectively? Consider using property management services or hiring a property manager.
Understanding these aspects can streamline your investment journey. Knowledge and preparation are keys to overcoming challenges in property investment. Utilise resources like online forums, seminars, and professional advisers to find detailed answers and tailor solutions to your unique situation.
Conclusion: Building a Sustainable UK Property Portfolio
Building a sustainable UK property portfolio requires strategic planning. An informed approach is crucial for long-term success. Focus on diversification to mitigate risks and enhance returns.
Keep these key points in mind:
- Conduct thorough market research.
- Set clear, achievable investment goals.
- Stay informed about property trends and regulations.
Regular portfolio assessments ensure alignment with your financial goals. Adapt your strategy in response to changing market conditions. Leverage technology and professional networks for efficient portfolio management.
A well-balanced property portfolio can provide financial stability and growth. Sustain your investment journey by continuously learning and adapting to new opportunities in the dynamic UK real estate market.


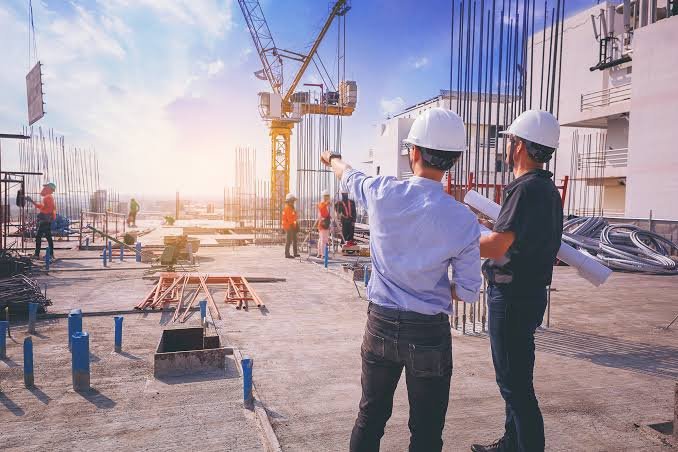
Whenever you remove or alter something that’s holding the house up. That’s the short answer, and it covers more work than most people expect, including plenty of projects that never go near a planning application. Any architects bromley homeowners work with will raise it early, because the calculations shape the design rather than following it.
Here’s when they’re needed, what they actually produce, and what it costs.
The Simple Test
Ask one question about the work. Is anything currently carrying load being removed, altered, or asked to carry more?
If yes, you need calculations. Planning permission has nothing to do with it. This is Building Regulations, and it applies whether your extension is permitted development or a full application.
Building Control will ask for a calculation pack before signing off structural work. Without one, the work doesn’t get approved, and unapproved structural work is a problem that surfaces at sale.
Work That Always Needs Calculations
Removing a load bearing wall. Including the rear wall of the house when you extend, which every rear extension involves. The beam replacing it needs sizing, and so do the supports at each end.
Any beam or lintel. Steel or timber. Span, section size and bearing all get calculated against the actual load, not selected from a table.
Loft conversions, every type. The existing ceiling joists were never designed to carry a floor. New floor beams, a ridge beam where the roof structure changes, and the structure for any dormer or gable all need designing.
Chimney breast removal. Removing a breast on the ground floor leaves the stack above unsupported, and a gallows bracket arrangement needs calculating rather than assuming.
New openings in existing walls. Wider doors, new windows, knocking two rooms together.
Foundations for the extension itself. Depth and design depend on ground conditions, proximity to trees and what’s already there.
Any double height space or floor void. On a recent Bromley new build the design included a void connecting the kitchen through to the basement level. Openings like that remove a chunk of structural floor plate, and the surrounding structure has to be designed to work without it. Impressive spaces are almost always the ones with the most engineering behind them.
Work That Usually Doesn’t
Non structural partition removal, where the wall carries nothing above it. Worth confirming rather than assuming, because internal walls in some construction types are doing more than they look like they’re doing.
Replacing a window in an existing opening, same size, existing lintel sound.
Internal fit out, decoration, kitchens and bathrooms.
Who Is Actually Qualified to Do This
Worth knowing, because the title isn’t protected in the way people assume.
Look for chartered status through the Institution of Structural Engineers or the Institution of Civil Engineers. The letters are MIStructE, CEng or MICE. Building Control treats calculations from a chartered engineer differently to a set of numbers from someone without that standing, and professional indemnity insurance sits behind the work.
Ask about insurance directly. If a design fails, the calculations are the document everyone goes back to.
What You Actually Receive
The output is a calculation pack, and it typically includes several things.
Load calculations showing what’s being carried and where it goes. Beam sizing and specification, giving the section, grade and required bearing length. Foundation design where new foundations are involved. Connection details where new structure meets old. And a set of structural drawings the builder works from and Building Control assesses.
That last point matters. The calculations aren’t paperwork produced to satisfy a regulation. They’re the instructions the builder uses to buy the right steel and build the right support.
What It Costs in 2026
Fees for extension work generally run £400 to £1,500, with straightforward single beam jobs at the lower end and complex multi element work at the upper.
| Item | Typical 2026 range |
| Single beam, straightforward | £400 to £700 |
| Standard rear extension package | £600 to £1,000 |
| Loft conversion package | £600 to £1,200 |
| Complex or multi element work | £1,000 to £1,500 plus |
Set against a build budget in the tens of thousands, this is one of the smallest line items in the project and one of the least sensible places to economise. An undersized beam is not a cost saving, it’s a defect that gets found by a surveyor at some point in the future.
Why Having the Engineer In House Changes the Design
Most practices outsource this, which means the design goes out, comes back with calculations, and any conflict between what was drawn and what’s structurally sensible gets resolved late.
Extension Architecture keeps a structural engineer in the same team as the design staff, which is uncommon across the industry. The practical effect is that beam spans get tested while the layout is still fluid, rather than after a client has fallen in love with a plan.
That matters more than it sounds. Beam cost rises sharply with span, and a design that removes an entire rear wall needs a considerably larger section than one retaining a pier. Catching that in week two costs nothing. Catching it after planning permission means either absorbing the cost or applying to amend an approved scheme.
The Ground Conditions Question
Foundation design depends on what’s under the site, and this varies enormously across London and the South East.
Standard foundations run around a metre deep. In clay soils, widespread across parts of Surrey and outer South London, that can rise to 1.5 metres or more. Groundworks on a standard single storey extension typically run £3,000 to £8,000, and clay pushes that upward.
Trees complicate it further. Clay shrinks and swells with moisture, and a mature tree within influencing distance changes the required foundation depth substantially. That’s a calculation, not a guess.
Bromley illustrates the point well. BR1 is dominated by Edwardian and 1930s houses on generous, often leafy plots, and mature trees near the rear of a property are common. It’s exactly the housing type where foundation design deserves attention before a builder prices the job. A structural engineer surrey projects rely on will want the same information before designing anything, because the clay conditions across Elmbridge and the wider county behave similarly.
Building Control: Two Routes
You have a choice, and it affects timeline.
The local authority route goes through the council’s own Building Control department. The alternative is an approved inspector, a private body carrying out the same statutory function.
Approved inspectors are often quicker and more flexible on site visit timing. Local authority Building Control has direct access to the council’s records on the property. Either is valid, and the decision is worth making early rather than during the build.
Party Walls Are a Separate Matter
Worth separating, because people conflate the two.
Structural calculations satisfy Building Regulations. The Party Wall Act 1996 is separate legislation about your neighbour’s rights.
Cutting into a shared wall to support new structure triggers notice under Section 3. Excavating near a neighbour’s foundation triggers Section 6. Two months notice for Section 3, one month for Section 6.
Your engineer’s calculations often form part of what a party wall surveyor reviews, but having calculations doesn’t discharge the party wall obligation, and serving notice doesn’t discharge the Building Regulations one. Both apply.
Getting the Order Right
The sequence that avoids rework is fairly consistent.
Survey the existing structure first, including foundations and party wall construction. Establish the planning position. Design the scheme with the structural strategy considered rather than assumed. Get calculations before finalising the drawings. Serve party wall notices early, because a neighbour with two months of warning behaves very differently to one given a fortnight.
Then tender. A builder pricing a scheme with calculations already done is pricing something real. A builder pricing a scheme without them is pricing an assumption, and the difference between those two numbers appears later as a variation.

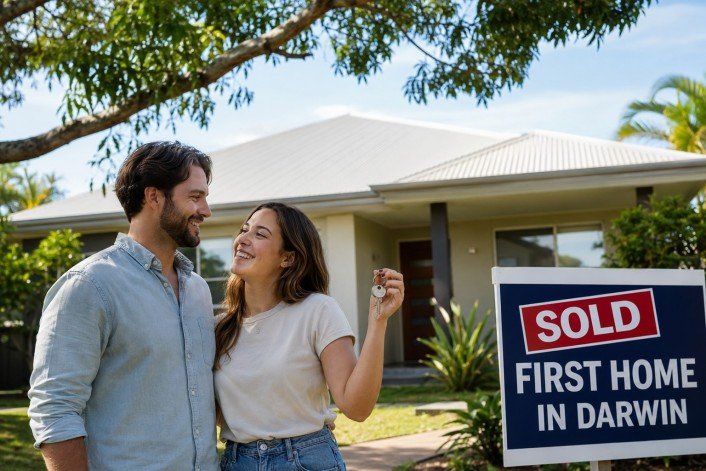
Purchasing a property for the first time can be a thrilling yet challenging experience, particularly in dynamic markets such as Darwin. This comprehensive guide serves to support first home buyers in making informed decisions by highlighting essential factors unique to the Darwin property landscape. Engaging with a trusted Monsoon Real Estate professional can significantly ease the process.
Understanding the Darwin Property Market
Darwin27s property market is influenced by factors such as local industry trends, economic growth, and demographic shifts. It is essential for first home buyers to understand these elements to select properties with strong growth potential and stability. The city’s tropical climate and lifestyle also impact housing styles and locations in demand.
Benefits of Buying Your First Home in Darwin
Darwin offers various advantages for first home buyers, including relatively affordable entry points compared with other Australian capitals. The city27s diverse communities and amenities add to its appeal. Additionally, government grants and incentives are available to assist those entering the property market for the first time.
Researching Locations Within Darwin
Selecting the right neighbourhood is critical. Prospective buyers should consider proximity to essential services, employment hubs, schools, and transport options. Exploring options with a reputable Darwin Real Estate Agent can provide expert insights into which suburbs currently demonstrate strong market performance.
Financing Your First Home
Understanding financing options is invaluable. First home buyers should explore mortgage products, including fixed and variable rates, to determine what best suits their financial situation. It is advisable to seek guidance from financial advisors or mortgage brokers to navigate government assistance programs such as the First Home Owner Grant.
Steps to Take Before Making an Offer
Before submitting an offer, thorough inspections and assessments are necessary. This includes evaluating the property27s condition, potential for capital growth, and any legal encumbrances. Engaging experienced inspectors and solicitors ensures that buyers avoid costly surprises.
Benefits of Working with Local Property Experts
Collaborating with local experts like Monsoon Real Estate delivers an edge through their knowledge of micro-markets and buyer preferences. Their negotiations expertise and network connections are assets in securing suitable properties at fair prices.
Exploring the Palmerston Market
Beyond Darwin itself, the neighbouring Palmerston area offers attractive opportunities for first home buyers. Known for its community amenities and growth trajectory, Palmerston represents a viable option for affordable properties. Engaging specialists familiar with real estate Palmerston NT can provide targeted assistance.
Key Considerations Regarding Property Types
Buyers must evaluate the pros and cons of various property types available in Darwin, such as townhouses, apartments, and detached houses. Factors to consider include maintenance obligations, potential for value appreciation, and lifestyle preferences.
Navigating Legal and Regulatory Requirements
Compliance with Northern Territory property laws is mandatory. Purchase contracts, disclosure obligations, and stamp duty regulations must be carefully reviewed. Legal advice should be sought to ensure all conditions are met before settlement.
Preparing for Settlement and Moving
The period between contract exchange and settlement involves crucial administrative steps, including final inspections and mortgage finalisation. Planning the logistics of moving and utilities transfer is essential to ensure a smooth transition into the new home.
Long-Term Considerations for First Homeowners
Owning a home involves ongoing responsibilities such as maintenance, insurance, and potential renovations. Budgeting for these costs and planning future property upgrades can enhance asset value and personal comfort.
Utilising Government Incentives for First Home Buyers
The Northern Territory Government offers various grants and stamp duty concessions tailored for first home buyers. Eligibility criteria and application processes should be reviewed early to maximise financial benefits during purchase.
Common Pitfalls to Avoid
First home buyers often encounter challenges related to underestimating total costs, overlooking due diligence, or rushing into decisions without expert advice. Awareness and avoidance of these pitfalls reduce the likelihood of buyer27s remorse.
Conclusion
Purchasing a first home in Darwin requires careful planning, research, and professional guidance. By leveraging local expertise from trusted entities such as Monsoon Real Estate, understanding market dynamics, and preparing financially, buyers can navigate the process effectively and secure a property that meets their needs for years to come.

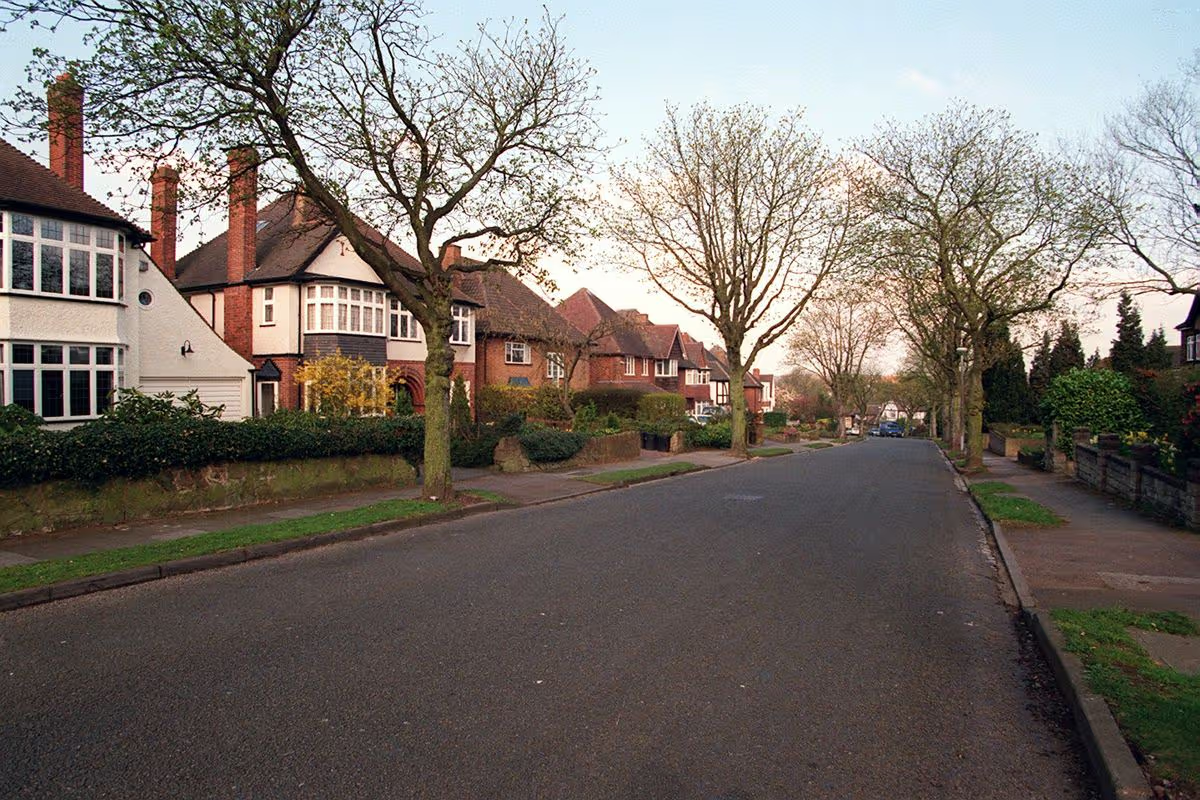
For many homebuyers, having enough space to accommodate changing family needs remains a major priority. While smaller, low-maintenance properties have become increasingly popular in some parts of the market, larger homes continue to attract buyers looking for flexibility, privacy and long-term practicality.
Sutton Coldfield is particularly well positioned for this type of demand. Its established residential neighbourhoods, strong selection of schools, extensive green spaces and connections to Birmingham make it attractive to families and professionals seeking more space without moving too far from the city.
For homeowners considering a move, working with Expert Local estate agents can provide useful insight into local property preferences and neighbourhood characteristics.
Why Space Remains Important to Buyers
The way households use their homes has changed significantly.
Bedrooms are no longer used exclusively for sleeping. A spare room might become a home office, study area, hobby room or guest bedroom. Larger kitchens can also function as dining and family spaces, while gardens provide valuable areas for recreation.
This flexibility means buyers may be willing to pay more for additional floor space if it allows the property to adapt to their lifestyle over several years.
Family Demand Supports Larger Properties
Families are one of the most obvious groups seeking larger homes.
Parents may require additional bedrooms as children grow, while separate living areas can provide greater privacy for different members of the household.
A larger property can also reduce the likelihood of needing to move again as the family changes.
In Sutton Coldfield, this can make larger houses particularly relevant to buyers looking for a long-term family home rather than a short-term purchase.
Home Working Has Increased the Value of Extra Space
Hybrid working has created another reason for buyers to consider larger properties.
A dedicated home office can make it easier to separate professional responsibilities from family life. In a smaller property, creating this separation can be challenging.
Larger homes can provide greater flexibility, whether that means converting a spare bedroom into an office or creating a workspace within an existing room.
For professionals who work from home regularly, this can be an important consideration when comparing properties.
Gardens Remain a Strong Attraction
Outdoor space can be particularly valuable for families.
A private garden provides an area for children to play, outdoor dining, gardening and relaxation. Larger gardens can also offer greater flexibility for homeowners who enjoy entertaining or outdoor hobbies.
Sutton Coldfield benefits from substantial green space, including Sutton Park, one of the largest urban parks in Europe.
The combination of private gardens and access to extensive public green space can make the area appealing to buyers who want a balance between suburban living and outdoor recreation.
Schools Influence Family Property Choices
For many families, school access is closely linked to the property decision.
Sutton Coldfield has a range of primary and secondary schools, meaning parents can consider education alongside property size, neighbourhood and transport.
A larger home in an area that provides convenient access to suitable schools can therefore offer several practical benefits at once.
Buyers should research individual school catchment arrangements and admission policies rather than relying solely on proximity when making decisions.
Transport Links Connect Sutton Coldfield With Birmingham
Larger homes do not necessarily mean sacrificing access to employment centres.
Sutton Coldfield railway station provides services towards Birmingham and surrounding areas, while road connections provide access to the wider West Midlands.
This connectivity can appeal to professionals who want a larger suburban home while remaining within reach of Birmingham’s employment, retail and cultural opportunities.
For drivers, access to major roads can also be important when commuting or travelling across the region.
Local Amenities Add to the Appeal
Families often want more than a large house.
Access to supermarkets, shops, restaurants, healthcare, leisure facilities and community services can make a significant difference to everyday convenience.
Sutton Coldfield has an established town centre and a range of local amenities across its residential neighbourhoods.
This means residents can benefit from having everyday services nearby while still enjoying the additional space associated with suburban properties.
Larger Homes Can Offer Greater Flexibility
One of the strongest advantages of a larger property is the ability to adapt it over time.
A room that begins as a nursery could eventually become a teenager’s bedroom, study or hobby room.
Similarly, a garage could potentially provide additional storage or workspace, subject to suitability and any required permissions.
This adaptability can be valuable to buyers thinking beyond their immediate requirements.
Downsizers Are Not the Only Buyers in the Market
While downsizing is influencing demand for smaller homes, larger properties continue to appeal to households moving in the opposite direction.
Some buyers may be moving from flats into houses after starting a family. Others may be relocating from smaller urban properties to gain additional space.
This creates demand across different stages of the property market.
For sellers of larger homes, understanding the needs of these buyers can help highlight the practical advantages of the property.
Larger Properties Can Also Attract Tenants
The appeal of additional space extends to the rental market.
Families renting for the medium or long term may look for properties with multiple bedrooms, gardens, parking and access to schools.
Professionals sharing accommodation may also value larger properties with multiple bedrooms and communal living areas.
For landlords, these properties can provide access to different tenant groups, although rental demand varies between neighbourhoods and property types.
Investment Potential Depends on the Right Property
Larger properties can provide opportunities for investors, but size alone does not guarantee strong returns.
Investors should consider:
- Purchase price
- Local rental values
- Property condition
- Maintenance costs
- Likely tenant profile
- Local competition
- Transport links
- School access
- Long-term demand
A well-positioned family home may have stronger rental appeal than a larger property in an area with limited amenities.
Parking Can Add Practical Value
As household sizes increase, so can the number of vehicles.
Off-street parking, garages and driveways can therefore be important features for families.
This is particularly relevant in suburban areas where residents may rely on cars for school runs, commuting and leisure activities.
For buyers comparing two similarly sized homes, parking provision can become an important differentiator.
Energy Efficiency Matters in Larger Homes
One consideration for buyers of larger properties is the potential cost of heating and maintaining additional space.
Energy efficiency can therefore become particularly important.
Insulation, windows, heating systems and EPC ratings can all influence ongoing household costs.
Buyers should consider not only the purchase price but also the likely cost of running the property over time.
For landlords, energy performance can also influence tenant expectations and the property’s overall rental appeal.
Green Space Supports Family Lifestyle
Sutton Coldfield’s access to green space is a significant part of its residential appeal.
Sutton Park provides extensive opportunities for walking, cycling, recreation and spending time outdoors.
For families, access to green space can complement having a private garden.
It also gives residents opportunities to enjoy outdoor activities without needing to travel far from home.
What Should Buyers Look For in a Larger Home?
A larger property should be assessed on more than bedroom count.
Potential buyers may want to consider:
- Flexible room layouts
- Garden size
- Parking
- Storage
- Home office potential
- School access
- Public transport
- Local amenities
- Energy efficiency
- Maintenance requirements
- Potential future adaptations
A property with slightly less floor space but a more practical layout may ultimately work better than a larger home with inefficient rooms.
Location Can Be Just as Important as Size
Having more space is valuable, but buyers should consider what they are gaining in exchange for it.
A large home in an isolated location may create additional travel requirements, while a slightly smaller property close to schools, transport and amenities could provide greater everyday convenience.
Sutton Coldfield offers different residential environments, allowing buyers to balance property size with accessibility and lifestyle.
Why Sutton Coldfield Continues to Attract Family Buyers
The appeal of larger homes in Sutton Coldfield is based on a combination of factors rather than size alone.
The area offers established residential neighbourhoods, schools, transport connections, local amenities and extensive green space.
For families seeking additional bedrooms, gardens and flexible living areas while remaining within reach of Birmingham, this combination can be particularly attractive.
Looking at the Long-Term Value of Space
For many buyers, purchasing a larger home is about planning for the future rather than simply meeting today’s needs.
Additional bedrooms can accommodate a growing family. Flexible rooms can support hybrid working. Gardens can provide outdoor space, while parking can make everyday routines easier.
These features can contribute to a property’s long-term practicality and appeal.
For homeowners, larger homes can provide room to adapt. For families, they can support changing needs. For landlords and investors, well-located larger properties can offer access to established family rental demand.
As household priorities continue to evolve, Sutton Coldfield’s combination of space, connectivity, schools, amenities and green surroundings should continue to make larger homes an important part of the local property market.

The Enduring Appeal of Batman: Why Every Generation Finds Its Own Dark Knight

Top Digital Marketing Agencies for Multi-Channel Campaign Success

How Technology Is Changing the Way We Learn to Drive

Keeping Dogs Clean After Muddy Outdoor Adventures

Improving Business Operations Through Service and Asset Management

Bond Street Area Rentals: A Neighbourhood Guide for First Time Luxury London Visitors

The 15 Highest-Paid Rugby Players in the World
Christopher Dare: The Untold Story of Engineer and Former Husband of Angela Rippon

How to Ensure Your Home is Valued Correctly for a Quick Sale

What Is Fanquer? The Digital Creator Platform Transforming Direct-to-Fan Engagement

Dr Jared Ross: Missouri Appeals Court Upholds Protection Order Over Graphic Torture and Murder Threats
Nancy Hallam: The Inspiring Life, Career, and Success Story Behind Ian Wright’s Wife
The 15 Highest-Paid Rugby Players in the World
Christopher Dare: The Untold Story of Engineer and Former Husband of Angela Rippon
How to Ensure Your Home is Valued Correctly for a Quick Sale
What Is Fanquer? The Digital Creator Platform Transforming Direct-to-Fan Engagement
Dr Jared Ross: Missouri Appeals Court Upholds Protection Order Over Graphic Torture and Murder Threats
Nancy Hallam: The Inspiring Life, Career, and Success Story Behind Ian Wright’s Wife
-
 Sports4 months ago
The 15 Highest-Paid Rugby Players in the World
-
Celebrity10 months ago
Christopher Dare: The Untold Story of Engineer and Former Husband of Angela Rippon
-
 Real Estate8 months ago
How to Ensure Your Home is Valued Correctly for a Quick Sale
-
 Technology4 months ago
What Is Fanquer? The Digital Creator Platform Transforming Direct-to-Fan Engagement
-
 Celebrity3 months ago
Dr Jared Ross: Missouri Appeals Court Upholds Protection Order Over Graphic Torture and Murder Threats
-
Celebrity10 months ago
Nancy Hallam: The Inspiring Life, Career, and Success Story Behind Ian Wright’s Wife
-
 Health8 months ago
Enclomimed 25 (Enclomiphene) – Effective PCT Protocol
-
 Celebrity10 months ago
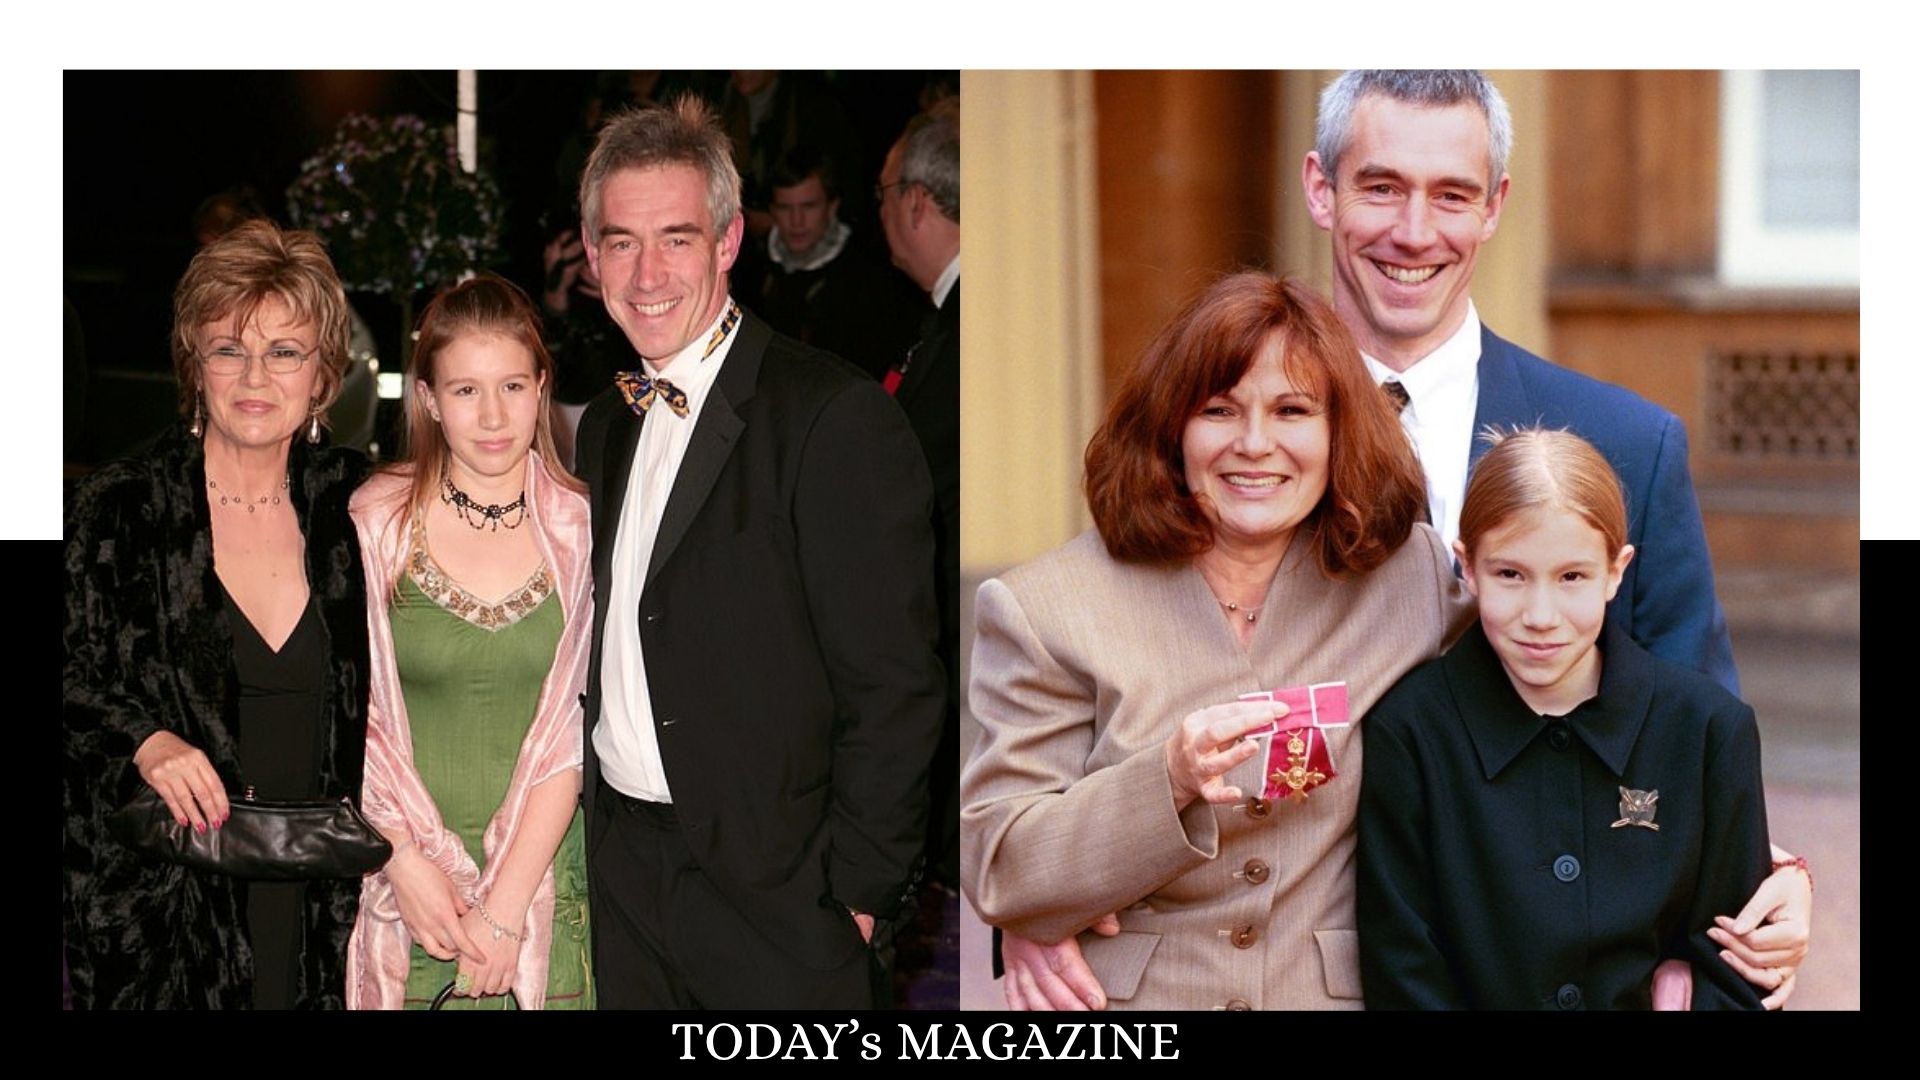
Who Is Maisie Mae Roffey? The Private Life, Family Story, and Quiet Success of Julie Walters’ Daughter