Business
What Separates a Child Lock Mylar Bag That Protects From Packaging That Just Looks Good

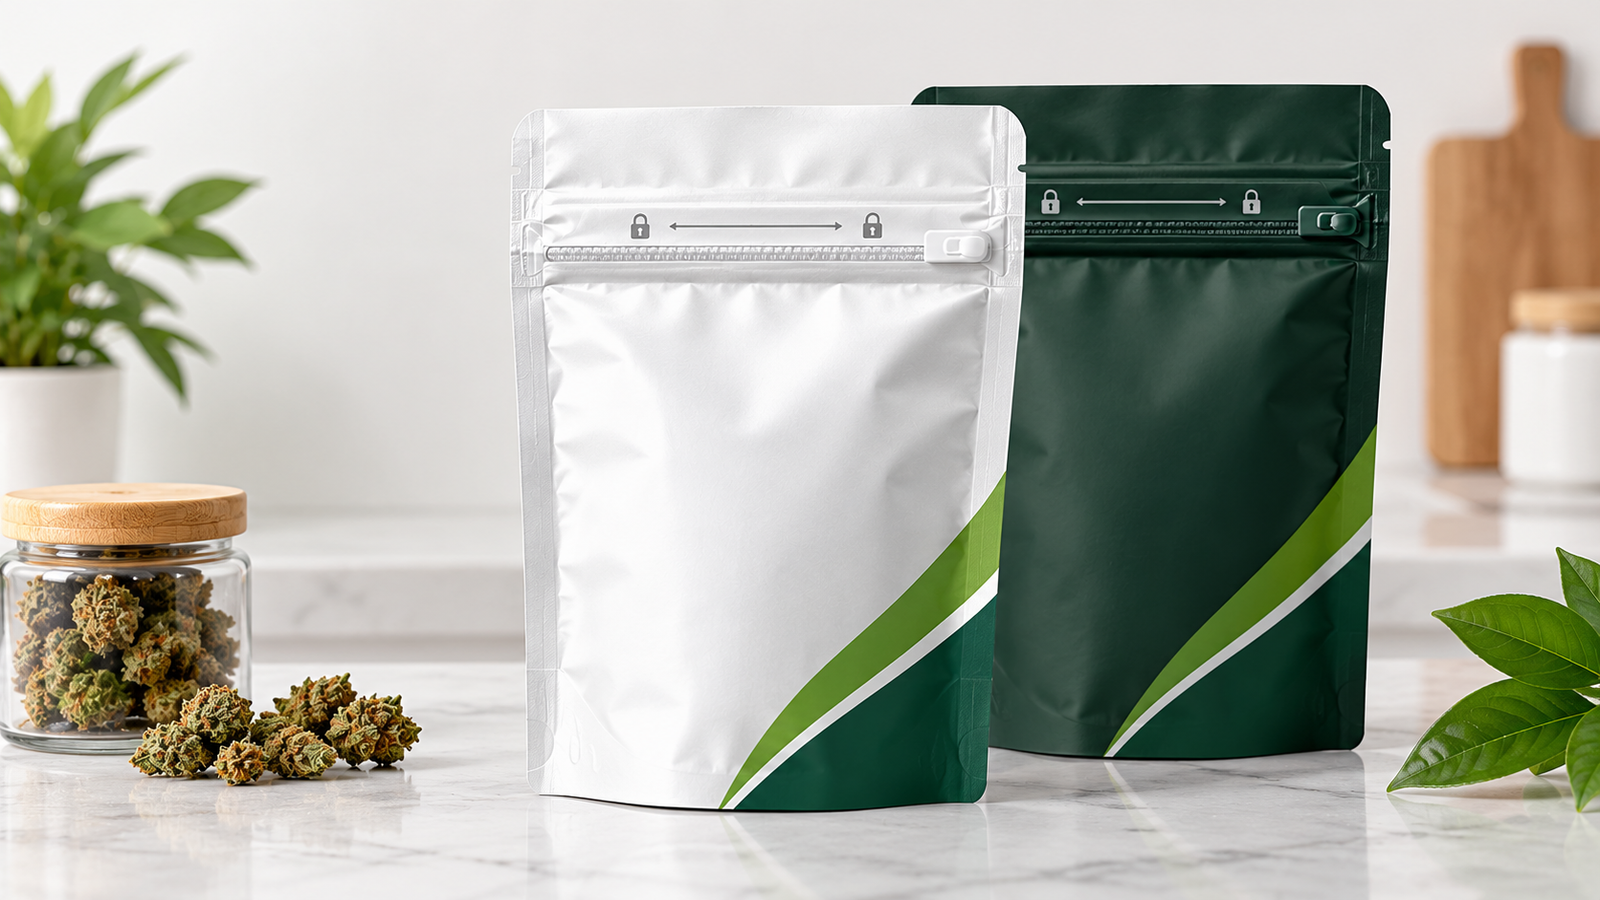
Packaging is expected to do much more than hold a product together. It must endure shipping, fit comfortably on a shelf, communicate a brand through its look and in the case of a group of controlled products, be hands-off in every way. This is where many businesses make a major error: assuming a child lock mylar bag is the right choice based on how the image looks in a mockup rather than what the product and regulations actually entail. It is not as late as many believe: it is the product itself, not the design file.
Understanding the Product Before the Packaging
An even closer look at what will be going into a pouch style is done before the style is even mentioned: the weight, the texture and sensitivity to moisture, oxygen and light.
Weight and Texture Considerations
Dense or heavier products require more robust films and stronger seals to ensure that they do not tear or break the seal during processing.
Moisture, Oxygen and Light Sensitivity
Sensitive products to air or light will spoil quicker in the incorrect barrier material, reducing shelf life and increasing returns.
Where Child Lock Mylar Bags Come In
Child Lock Mylar Bags are barrier protection, but include a mechanism which, in fact, is extremely hard to be opened by young children and this is why they have come to be just short of default in a number of regulated categories.
Material Structure and Shelf Performance Go Hand in Hand
The next choice after mapping out the needs of the product is the film structure that it will consist of, how many layers it comprises, the barrier properties it provides and how it supports itself when it is actually on a shelf and not in a warehouse.
Barrier Properties and Film Thickness
The combination of the right layers is against oxygen and moisture without inflating costs of production. Might be too thin and the product spoils prematurely; might be too thick and the margins are just hit without much real gain.
Base, Footprint and Visibility
The base gusset of a pouch will determine whether the pouch will stand upright and will maintain its shape once filled and this will have a direct impact on merchandising. Stable footprint and visible window or panel also contribute to a perceivable difference in shelf visibility.
Deciding Between Custom Child Resistant Mylar Bags
Custom Child Resistant Mylar Bags are competing with stock pouches that more brands are customizing, as they can be sized, finished and printed to specific brands without compromising the compliance features that regulated products demand.
How Recognizable Brands Treat Packaging as Part of Their Identity
Not all packaging decisions are functional because with well known brands, packaging is an aspect of the product experience. It is useful to look at how bigger companies tackle it, although it is not relevant to their industry.
Kwick Packaging
Companies desiring the same brand identity and functionality, but in a regulated or sensitive product, tend to deal with suppliers such as Kwick Packaging that sells Child Resistant Mylar Bags Wholesale and includes custom printing and quality control. Those customers who have switched over tend to feel it right away:
“Our customers often comment on how well-designed and functional these custom 8 oz Mylar bags are. It’s a win-win situation for us and them. These 8 oz bags are a reflection of our brand’s personality. They’ve given our business a unique edge. Will ship again & again.” Nicholas Hope
“We recently collaborated with Kwick Packaging to design custom mailer boxes that included our logo and personalized greetings for each client. The boxes were hugely popular! They arrived looking sharp, and Kwick Packaging’s customer service was excellent. Their crew was quite helpful in designing mockups and ensuring that the order went well.” Anna
Pandora
Pandora has established a brand image of gift-wrapping that is both high-end and luxurious: small boxes, tactile surfaces and consistent branding across all touchpoints, to remind them of how much packaging matters in a first impression.
Packlane
Packlane has expanded to provide smaller and mid-sized brands with access to fully custom and print-on-demand packaging that does not require large order quantities like larger manufacturers typically demand and brand-specific design has become available at nearly any scale.
Closures, Shipping and the Details That Get Overlooked
The right closure and the right to survive shipping are two of the least discussed aspects of packaging choice, although they usually define the first impression of a customer with a product as good or bad.
Matching Closures to Product Use
A zipper is used to reseal snacks and pet treats that can be resealed and a spout can be used to seal off liquids; a tin tie is suitable to use with coffee and a heat seal is used to seal single use or tamper evident products. The misguided decision may spoil a well-thought-out pouch.
Building for Real Shipping Conditions
A pouch may work very well on a shelf and fail during transit should the film and seals not have been designed to stack, compress and endure rough handling throughout a supply chain. These issues are identified during testing in actual shipping conditions prior to them becoming returns.
Sourcing Custom Printed Mylar Bags at Scale
When a company has to produce on a large scale, it is important to collaborate with a manufacturer who maintains quality in large batches as much as the initial design. Ordered Custom Printed Mylar bags that are done in volume require the same seal and print quality on unit 10,000 as unit one.
Choosing a Manufacturer: What Actually Matters
Even a well-specified pouch may end up failing when the manufacturer of the pouch lacks the proper equipment or process. Some considerations to make before making a big order:
- On-site production and material knowledge.
- Stability in printing large batches.
- Quality of seal and pouch construction.
- Customized dimensions and thickness.
- Pre-production sampling and prototyping.
- Capacity to produce without compromising consistency.
- Communication and support throughout the order
Testing Before You Commit to a Full Run
The most frequent and costly error in packaging choices is not going through the sample stage. Specs alone will not indicate issues, which can only be discovered during a trial run with the actual product, not a placebo.
Fill and Seal Testing
Conducting a practical fill-and-seal exercise with the planned product reveals seal strength or fit problems, unseen on paper.
Drop and Transportation Testing
A simulation of the process of stacking, vibrating and handling of a pouch will be done in transit to identify weak seams or structural problems before a large quantity is created.
Confirming Compliance Before Bulk Production
In production of regulated products, verification that a sample meets the child-resistance test procedures prevents expensive rework and compliance holds-ups.
Conclusion
Balanced packaging will provide protection, functionality, presentation as well as a manufacturing partner that can deliver protection at scale. Achieving all of these correctly on a child lock mylar bag, including the product and not the artwork, is what makes the difference between a performing and a nondemanding packaging.
FAQs
1. Do custom child-resistant mylar bags cost more than regular ones?
Custom options tend to be expensive initially because of tooling and print setup but the difference is smaller at wholesale levels and the additional compliance and branding value tends to offset the difference.
2. Why is a pouch child-resistant and not resealable?
The packaging must satisfy certain testing requirements that demonstrate that most young children can not open it within a designated time but adults can with reasonable effort – a resealable zipper alone does not pass the bar.
3. What is the time taken to order a sample before ordering a bulk?
Most manufacturers have timelines that are dependent on how reputable the supplier is, but most reputable suppliers have the ability to turn around a sample or a small run of a trial within a few weeks, which is well worth the wait before investing in a large production run.

Navigating the world of general liability insurance is crucial for electrical contractors. This comprehensive General Liability Class Code For Electrical Contractors guide will provide you with a practical, step-by-step approach to selecting the right class code based on your project types and service areas. You’ll learn how specific codes impact your insurance premiums and policy coverage, ensuring you’re adequately protected.
In this guide, we will delve into the importance of understanding class codes, how to identify the right one for your business, and the nuances of insurance coverage that can significantly affect your operations.
Understanding General Liability Insurance
General liability insurance is essential for electrical contractors, providing coverage for various risks associated with electrical work. It protects against claims of bodily injury, property damage, and personal injury that may occur during the course of business operations.
Why Class Codes Matter
Class codes are numerical identifiers assigned to different types of businesses and their activities. For electrical contractors, selecting the appropriate class code is vital because:
- Risk Assessment: Each code corresponds to a level of risk, influencing your insurance premium. The more specialized or hazardous your work, the higher the classification, potentially leading to increased costs.
- Coverage Specificity: Different codes relate to specific services, which directly affects the coverage scope. Certain activities may require additional endorsements to the standard policy.
- Compliance: Using the wrong class code may lead to complications, including denied claims or increased premiums. Regular audits by insurance companies may further scrutinize your chosen codes, emphasizing the importance of accuracy.
It’s essential to choose the right class codes to adequately protect your business and ensure compliance with industry regulations.
Step-by-Step Process for Choosing the Right Class Code
Step 1: Identify Your Services
Start by listing all services your electrical contracting business provides. This may include:
- Residential electrical work
- Commercial electrical installations
- Industrial electrical services
- Specialty services (e.g., data cabling, home automation)
- Emergency repair services
- Testing and inspections
A well-defined list can prevent confusion later and help you engage effectively with insurers to clarify your operations.
Step 2: Research Class Codes
Once you have a complete list of your services, research the standard class codes used in the electrical contracting industry. Here’s a brief overview of common codes for electrical contractors:
- Elect 001: General electrical contractors (low-risk residential)
- Elect 002: Commercial electrical work (medium risk)
- Elect 003: Industrial electrical contracting (high risk)
- Elect 004: Specialty services such as solar panel installations or low-voltage work
- Elect 005: Data and telecommunications installations
Make sure to note the definitions associated with each code, since even small differences between services can affect risk levels. For example, solar installations might require additional safety measures that affect insurance premiums.
Step 3: Consult With Industry Experts
Consider consulting with an insurance agent or broker who specializes in policies for electrical contractors. They can provide insights into which class codes align with your unique business operations, as well as offer advice on coverage needs. They may conduct a risk analysis, which could uncover factors that you might not have considered initially.
Step 4: Review Your State’s Regulations
Different states may have specific rules and regulations regarding class codes for insurance. Familiarize yourself with your state’s requirements to ensure compliance. Check with local business associations or state insurance departments for guidance. For example, states like California may have stricter regulations regarding certain electrical work due to higher seismic activity, impacting insurance costs and requirements.
Step 5: Evaluate Your Risk Profile
Understanding your risk profile is crucial. Assess the following factors:
- Project Types: Are you handling high-voltage installations or primarily residential wiring? Higher-risk projects typically require more comprehensive coverage.
- Business Size: A larger business may involve more significant risk due to the number of employees and scale of projects. Large teams usually mean increased safety and compliance risks.
- Service Area: Operating in urban versus rural settings can often affect the frequency of claims. Urban areas may have higher traffic risk, while rural areas might present challenges in responding to emergencies promptly.
Evaluate historical claims data if available, as this can inform future decisions on coverage and class codes.
Step 6: Choose the Right Class Code
Using the information gathered in the previous steps, select the class code that most accurately reflects your primary business operations. Be truthful about the services you provide to avoid complications in case of a claim. It’s often helpful to provide detailed descriptions to your insurer to ensure clarity.
Step 7: Update Your Policies Regularly
As your business grows or diversifies, your class code may need to change. Regularly review your insurance policies and update your class codes as necessary to ensure proper coverage. It’s recommended to conduct these reviews annually or whenever a significant change occurs in your operations, such as expanding service areas or introducing new services.
Types of Coverage for Electrical Contractors
Understanding types of coverage associated with general liability for electrical contractors is essential. Not all coverage is created equal, and knowing the differences can impact your overall protection strategy:
- General Liability: Covers basic liability risks, including bodily injury and property damage. It’s the cornerstone of protection for contracting businesses.
- Professional Liability Insurance: Provides coverage if a client claims negligence or errors in your professional services. This is crucial for projects that require extensive planning or consultation.
- Workers’ Compensation: Mandatory coverage for employees, providing medical benefits and wage replacement in case of work-related injuries. This is especially important in high-risk environments where electrical work can lead to accidents.
- Commercial Auto Insurance: Essential if you use vehicles for your business operations, covering damage to vehicles and liabilities. Given the mobility of electrical contractors, having comprehensive auto insurance is vital.
- Equipment Insurance: Valid for protecting your tools and equipment against theft or damages while on the job site, focusing on the tools that are often expensive and integral to your operations.
Frequently Asked Questions
What is a class code?
A class code is a numerical identifier assigned to businesses based on their industry and associated risks, affecting insurance premiums and coverage.
How do I find the correct class code for my electrical contracting business?
Start by listing the services you offer, researching common class codes for electrical contractors, and consulting with insurance professionals for guidance.
Can my class code change over time?
Yes, as your business evolves, services may change, necessitating updates to your class code to reflect your current operations accurately.
What happens if I select the wrong class code?
Selecting the incorrect class code can lead to claims being denied, improper coverage, or increased premiums over time. This mistake might have long-term financial repercussions, especially for claims that may arise during significant contract work.
Is general liability insurance mandatory for electrical contractors?
While not always legally required, having general liability insurance is crucial for protecting your business from potential liabilities and is often needed for contracts. Clients may expect proof of insurance before hiring you.
How does my location affect my class code?
Different states might have varying risks associated with certain types of work, impacting the class codes and premiums associated with electrical contracting. For instance, states prone to severe weather may necessitate different coverage due to higher property damage risk.
Conclusion
In conclusion, selecting the right general liability class code for electrical contractors is a critical process that requires careful consideration of your services, risk profile, and industry regulations. By following the steps outlined in this General Liability Class Code For Electrical Contractors guide, you will be well-equipped to make informed decisions that protect your business.
Remember to regularly review and update your class codes as your business evolves. Doing so will ensure that you maintain proper coverage while navigating the complexities of the insurance landscape. For further information on general liability insurance tailored to your needs, consult our General Liability Class Code For Electrical Contractors guide.
Business
100 Fix and Flip No Credit Check: What US Real Estate Investors Need to Know Before Applying

Real estate investment moves on timing. When a distressed property becomes available at the right price, the window to act is often narrow. Traditional lending institutions are rarely equipped to meet that window. Their approval timelines, documentation requirements, and credit scoring processes are built for stability and predictability — not for the fast-moving decisions that define fix and flip investing. For investors working outside conventional credit profiles, this gap between opportunity and available capital has long been a real operational problem, not just a minor inconvenience.
Over the past several years, a category of lending has grown specifically to serve this gap. These are financing products designed for real estate investors who need acquisition and renovation capital quickly, and who may not qualify — or simply do not want to go through — traditional credit-based underwriting. Understanding how these products actually work, what they evaluate in place of credit, and what investors should prepare for before applying is increasingly practical knowledge for anyone active in the US fix and flip market.
What 100 Fix and Flip Loans No Credit Check Actually Means in Practice
The term “100 fix and flip loans no credit check” describes a specific type of real estate investment financing that covers the full cost of both property acquisition and renovation without using the borrower’s credit score as the primary approval factor. This is a meaningful structural difference from conventional loans. Rather than assessing the borrower’s personal financial history as the dominant underwriting variable, these loans evaluate the asset itself — the property being purchased, its current condition, its projected value after renovation, and the feasibility of the investor’s plan.
For investors who want a grounded starting point before engaging with any lender, reviewing a 100 Fix And Flip Loans No Credit Check overview can help clarify what these structures typically include, how they differ from partial-coverage hard money loans, and what documentation lenders in this category generally require from applicants.
The “no credit check” element does not mean the lender is operating without due diligence. It means credit history is deprioritized in favor of asset-based evaluation. Some lenders in this space conduct a soft pull for identity verification but do not use credit score thresholds as a qualifying barrier. Others skip credit inquiry entirely. In both cases, the lending decision rests primarily on whether the deal itself is sound — the property’s location, its purchase price relative to market comparables, and the credibility of the projected after-repair value.
Why Asset-Based Underwriting Is Central to This Loan Type
Traditional mortgage underwriting assumes that the borrower’s financial history is the most reliable predictor of repayment. For primary residences and long-term owner-occupied financing, this assumption has reasonable logic behind it. Fix and flip investing operates differently. The repayment is not driven by the borrower’s monthly income over thirty years — it is driven by the successful completion of a renovation project and the profitable sale of the property, typically within a short holding period.
Asset-based underwriting aligns more naturally with this model. A lender evaluating a fix and flip deal is asking different questions: Is the property in a market with active buyer demand? Is the purchase price positioned correctly relative to what the property will sell for once renovated? Does the investor have a realistic plan and timeline for completing the work? These questions produce a more relevant picture of repayment risk than a credit score does in this context. This is why experienced fix and flip lenders have built underwriting models that center the asset rather than the borrower’s personal financial profile.
The Role of After-Repair Value in Loan Structuring
After-repair value, commonly referred to as ARV, is the estimated market value of a property once all planned renovations are complete. For 100 fix and flip loans with no credit check, ARV is not just a reference figure — it is typically the central metric around which the entire loan is structured. The lender uses ARV to determine how much capital the deal can support, what the risk exposure looks like at various stages of the project, and whether the numbers leave enough margin to cover their position if something goes wrong.
Investors should understand that a higher ARV does not automatically translate into approval or larger loan amounts. Lenders apply their own thresholds and calculations, and they will assess whether the ARV projection is supported by real comparable sales in the local market. Overstated ARV estimates are one of the most common reasons deal financing falls apart during underwriting, even in asset-based lending environments. Arriving with well-researched comparables and a realistic renovation scope is not optional — it is foundational to how these transactions are evaluated.
How Full Coverage Differs from Partial Hard Money Financing
Many investors who are new to non-traditional real estate financing assume that all hard money or private loans in the fix and flip space work similarly. In practice, there are meaningful differences between products that offer partial coverage and those that offer full acquisition and renovation funding. A standard hard money loan might cover a percentage of the purchase price, leaving the investor responsible for contributing cash toward both acquisition and renovation costs. Full-coverage 100 fix and flip loans are structured to eliminate or significantly reduce that out-of-pocket requirement.
This distinction matters because it directly affects who can access capital. Investors with strong deal-finding skills and project management experience but limited personal liquidity have historically been locked out of deals by cash contribution requirements. Full-coverage loan structures open the door to investors who can identify and execute profitable deals but are not in a position to deploy significant personal capital at the front end of each transaction.
Understanding Loan Structure and Draw Schedules
In a full-coverage fix and flip loan, acquisition funding and renovation funding are typically handled differently. Acquisition funds are released at closing to purchase the property. Renovation funds are usually held in reserve and distributed in stages, or draws, as construction milestones are completed and verified. This draw structure serves a specific purpose: it protects the lender from over-funding a project before the work is done, and it creates a checkpoint system that keeps projects on track.
For investors, understanding draw schedules before committing to a loan is operationally important. Delays in draw approvals can create cash flow gaps that slow construction timelines and increase holding costs. Knowing how a lender handles inspections, how quickly they process draw requests, and what documentation they require at each stage allows investors to plan their contractor relationships and project timelines accordingly. A loan with favorable terms on paper can create real friction in execution if the draw process is slow or administratively burdensome.
Short Holding Periods and Repayment Expectations
Fix and flip loans are short-term instruments. They are not designed to be held for extended periods, and lenders structure them with this expectation built in. Typical terms run from several months to roughly a year, with the expectation that the investor will complete renovations, list the property, close a sale, and repay the loan within that window. Extensions are sometimes available but usually come with additional costs.
This means that timeline management is not just a project management concern — it is a financial one. Delays in renovation, market softness that extends the time on market, or complications in the sale process all compress the margin between what the property sells for and what the investor owes. Investors who consistently manage projects to realistic timelines are far better positioned to use these loan products profitably and repeatedly. The United States Department of Housing and Urban Development provides regional market data that can help investors assess realistic timelines in specific local markets before committing to a project scope.
What Lenders in This Space Typically Evaluate Instead of Credit
When credit score is removed as a primary underwriting variable, lenders in the 100 fix and flip no credit check space replace it with a different set of evaluation criteria. Understanding what these criteria are — and how to present them clearly — is one of the most practical things an investor can do before approaching a lender. The evaluation framework varies by lender, but several factors consistently appear across the category.
• The property’s purchase price relative to its estimated after-repair value, with lenders assessing whether enough spread exists to protect their position and allow the investor a reasonable return.
• The investor’s demonstrated experience with similar projects, including whether they have completed renovations on schedule and sold properties profitably in the past.
• The quality and detail of the renovation scope, including whether contractor relationships are in place and whether the budget reflects realistic local labor and materials costs.
• The strength of the local market, including absorption rates, comparable sale prices, and days on market for similar properties in the target neighborhood.
• The investor’s exit strategy, meaning not just that they intend to sell, but that there is evidence the market will support a sale at the projected price within a reasonable timeframe.
Investors who approach lenders with a well-organized deal package — clear comparables, a realistic renovation budget, a credible timeline, and evidence of prior project experience — move through underwriting more efficiently. These loans are not approval-guaranteed products. They are asset-evaluated products, and the quality of the asset presentation directly influences both approval outcomes and the terms that result.
Practical Considerations Before Applying
Applying for a 100 fix and flip loan with no credit check is not a complicated process, but it rewards preparation. Investors who treat the application as a business presentation — organized, realistic, and grounded in verifiable data — are far more likely to receive terms that actually support a profitable deal. A few practical considerations apply regardless of which lender an investor approaches.
Renovation budgets should be detailed and should account for contingency. Lenders who specialize in this space have reviewed enough projects to recognize when a budget is understated, and an implausible budget raises questions about the investor’s judgment across the entire deal. Similarly, ARV projections should be defensible with recent comparable sales, not aspirational estimates based on best-case conditions.
Investors should also review the fee structure and cost of capital carefully. Interest rates on short-term fix and flip loans are higher than conventional mortgage rates, and there are typically origination fees, draw fees, and extension fees that affect the true cost of the loan. A deal that looks profitable when the financing cost is underestimated can quickly erode when actual carrying costs are calculated accurately.
Closing Thoughts
Fix and flip investing operates in a different risk and timing environment than most other forms of real estate activity. The financing tools that support it need to match that environment — fast, flexible, and focused on the deal rather than the borrower’s credit file. The growth of 100 fix and flip loans no credit check as a recognized product category reflects a real shift in how private capital is being deployed in the US residential investment market.
These products are not without complexity, and they are not appropriate for every investor or every deal. But for investors who understand how asset-based underwriting works, who approach deals with realistic projections and organized documentation, and who manage project timelines with discipline, this category of financing offers genuine access to capital that would otherwise remain out of reach. The key is entering the process informed — knowing what lenders in this space are actually evaluating, what the loan structure requires operationally, and how to build a deal package that presents the investment clearly and credibly.
Investors who take the time to understand these mechanics before they need capital are in a far stronger position than those who search for financing only after a deal is under contract. In a market where timing matters, that preparation often makes the difference between closing a profitable project and losing the opportunity entirely.
Business
The 10-Point Checklist Every US Business Owner Needs Before Choosing Executive Benefits Solutions
When a business reaches the point where it needs to attract, retain, or reward senior leadership, the compensation conversation shifts considerably. Base salary and standard health coverage are no longer sufficient on their own. Executives and key employees expect something more structured, more deliberate, and more aligned with the long-term trajectory of the company. This is where executive benefits enter the picture — not as a luxury, but as a functional tool for business continuity and talent stability.
The challenge for most business owners is that this space is unfamiliar territory. Unlike payroll benefits that follow well-defined regulations and carrier structures, executive benefits involve a layered mix of tax treatment, plan design, legal compliance, and business strategy. Making the wrong choice — or choosing without enough context — can result in misaligned expectations, regulatory exposure, or benefit structures that fail to deliver what they were designed to do.
Before committing to any plan or provider, business owners benefit from working through a clear set of considerations. The following checklist is designed for that purpose: to slow the process down, surface the right questions, and ensure that any decision made is grounded in operational reality rather than a sales pitch.
1. Understand What Executive Benefits Actually Cover
The term “executive benefits” encompasses a wide range of financial tools and arrangements that go beyond standard employee benefits. These typically include nonqualified deferred compensation plans, supplemental executive retirement plans (SERPs), executive life insurance, disability income protection at higher income levels, and various equity-adjacent arrangements. Each of these serves a distinct purpose, and no single structure fits every organization. Reviewing a reliable Executive Benefits Solutions overview can help business owners understand which categories apply to their situation before they begin comparing providers or plan types.
Why the Definition Matters Before the Selection
Business owners often enter conversations with advisors already anchored to one type of plan — usually whichever one was mentioned first. This narrows the decision before it should be narrowed. When an owner understands the full menu of available options, they are better equipped to ask whether a recommended plan is actually the right fit or simply the most convenient one to offer. The distinction matters enormously over a ten or twenty-year horizon.
2. Confirm the Business Structure and Tax Classification
The legal and tax structure of the business — whether it is an S-Corp, C-Corp, partnership, or LLC — has a direct bearing on which executive benefit arrangements are available and how they are treated for tax purposes. Some plans, such as certain nonqualified deferred compensation structures, function differently depending on whether the business is privately held or publicly traded. Others carry tax deduction implications that vary by entity type.
Alignment Between Plan Design and Entity Structure
A plan that works well for a C-Corp owner may create unintended tax consequences for an S-Corp owner. This is not a minor administrative detail — it affects the actual value of the benefit over time. Any executive benefits arrangement should be reviewed with both a benefits specialist and a qualified tax advisor who understands the specific entity structure of the business.
3. Identify Who the Benefit Is Actually Designed to Serve
Executive benefits can be designed to serve the business owner, a small group of senior executives, or a single key employee. The purpose changes the design. A benefit structured to retain a high-performing COO over five years looks different from one designed to fund a business owner’s retirement or protect the company in the event of a key person’s death or disability.
The Risk of Generalized Plans
One of the most common errors in this process is applying a generalized plan to a specific situation. Providers sometimes offer templated structures that have broad applicability but may not address the precise need in front of them. Business owners should be able to articulate, in plain terms, what outcome they are trying to achieve — and a good advisor should be able to confirm whether the proposed solution matches that outcome.
4. Evaluate Plan Funding Methods
Executive benefit plans are funded in various ways, and the funding method affects both the financial exposure for the business and the security of the benefit for the recipient. Some plans use corporate-owned life insurance as a funding vehicle. Others are informally funded through general corporate assets or formally structured with trusts. Each approach carries different implications for balance sheet treatment, cash flow requirements, and what happens if the business is sold or the executive departs before the benefit matures.
Cash Flow Timing and Business Continuity
Funding is not a one-time decision. It requires ongoing commitment from the business, and that commitment should be evaluated against realistic projections of company cash flow. A plan that looks affordable in year one but becomes a financial burden in year four creates operational risk rather than stability. This evaluation should be done as part of the initial design conversation, not after the plan is in place.
5. Review ERISA and Compliance Requirements
Many executive benefit arrangements are specifically structured to fall outside the requirements of the Employee Retirement Income Security Act (ERISA), which governs most qualified retirement plans. The U.S. Department of Labor provides regulatory guidance on benefit plan asset rules, and understanding how these interact with nonqualified plans is essential before any arrangement is finalized. Non-ERISA status allows for greater flexibility in plan design, but it also means the business bears more responsibility for documentation and compliance.
Documentation as Ongoing Protection
The compliance dimension of executive benefits is not a one-time setup task. Plans require properly drafted agreements, consistent administration, and periodic review as tax law and regulatory requirements evolve. Business owners should ask any prospective advisor or provider how ongoing compliance is handled — and who is responsible for monitoring changes that could affect the plan’s structure or tax treatment.
6. Assess the Provider’s Experience With Privately Held Businesses
Executive benefits are often discussed in the context of large publicly traded corporations. However, the majority of businesses that need these arrangements are privately held, family-owned, or owner-operated companies. The planning considerations are meaningfully different. Business succession, buy-sell agreements, key person risk, and the owner’s own retirement planning often intersect with executive benefit design in ways that don’t apply to corporate environments.
7. Understand the Vesting and Retention Mechanics
The retention value of an executive benefit depends largely on how vesting is structured. A plan that vests too quickly provides limited incentive for an executive to stay. One that vests too slowly may not be attractive enough to recruit with. The structure should match the actual retention goal — whether that is three years, five years, or tied to a specific business milestone such as a transition event or sale.
What Happens When an Executive Leaves Early
This is one of the most important questions to resolve during plan design, not after a departure occurs. If an executive leaves before the plan matures — voluntarily, involuntarily, or due to disability — the plan documents need to clearly define what happens to the benefit. Ambiguity in this area leads to disputes and, in some cases, significant financial loss for one or both parties.
8. Clarify How the Plan Interacts With Existing Benefits
Most businesses already have some form of qualified retirement plan in place — a 401(k), profit-sharing plan, or similar structure. Executive benefits should be designed with these existing arrangements in mind. An executive who is already maximizing contributions to a qualified plan has different supplemental needs than one who is not. Duplication of coverage, contribution limits, and the overall benefit picture should be mapped out before any new plan is added.
9. Plan for Business Transitions From the Start
Executive benefits do not exist in isolation from the broader trajectory of the business. A plan that works well for the business in its current form may become problematic if the business is sold, merged, or transferred to the next generation. These scenarios should be addressed during the design phase, not treated as future problems to solve later. Some executive benefits solutions can be structured to protect both the business and the recipient across ownership transitions if planned correctly from the beginning.
10. Establish Clear Review Cycles
No executive benefit plan should be treated as permanent and self-managing. The needs of the business change, the tax environment evolves, and the role or status of the executive may shift over time. A plan that was well-designed five years ago may no longer reflect current business priorities or legal requirements. Establishing a defined review schedule — typically annual or tied to significant business events — is an essential part of responsible plan management.
Who Should Be in the Room During Reviews
Reviews are most effective when the right people participate. This typically includes the business owner, the benefits advisor, the company’s tax counsel, and any executive who is a plan participant. When these parties review the plan together, gaps are identified sooner, and adjustments can be made before they become costly corrections.
Closing Thoughts
Choosing the right executive benefits arrangement is not a transaction — it is a planning process that requires deliberate thought, qualified guidance, and a clear understanding of what the business is actually trying to accomplish. The checklist above is not exhaustive, but it covers the ground that most business owners overlook when they move too quickly into plan selection without first establishing a solid foundation of context.
The businesses that benefit most from executive benefit planning are those that treat it as an extension of their broader business strategy rather than a standalone financial product. When the plan design reflects the company’s real goals — retaining specific people, funding an owner’s exit, protecting the business against key person risk — it delivers consistent value over time. When it does not, it becomes an administrative and financial burden that rarely delivers what was promised.
Taking the time to work through these ten considerations before making a commitment is the most straightforward way to avoid that outcome. The conversation with an advisor will be more productive, the design will be more precise, and the plan will be more likely to serve its intended purpose over the long term.

What Separates a Child Lock Mylar Bag That Protects From Packaging That Just Looks Good

How to Choose the Right Charity or Community Cause to Support?

RingConn Smart Rings for Women: How to Choose the Right Model

Aussie-Bound Parcels: The Smart Seller’s Shipping Playbook for Australia
Kitchen Cabinet Brands: How to Choose the Right Cabinets for Your Home

Fees Explained: What You Pay for With a Managed Portfolio

The 15 Highest-Paid Rugby Players in the World
Christopher Dare: The Untold Story of Engineer and Former Husband of Angela Rippon

How to Ensure Your Home is Valued Correctly for a Quick Sale

What Is Fanquer? The Digital Creator Platform Transforming Direct-to-Fan Engagement

Dr Jared Ross: Missouri Appeals Court Upholds Protection Order Over Graphic Torture and Murder Threats
Nancy Hallam: The Inspiring Life, Career, and Success Story Behind Ian Wright’s Wife
The 15 Highest-Paid Rugby Players in the World
Christopher Dare: The Untold Story of Engineer and Former Husband of Angela Rippon
How to Ensure Your Home is Valued Correctly for a Quick Sale
What Is Fanquer? The Digital Creator Platform Transforming Direct-to-Fan Engagement
Dr Jared Ross: Missouri Appeals Court Upholds Protection Order Over Graphic Torture and Murder Threats
Nancy Hallam: The Inspiring Life, Career, and Success Story Behind Ian Wright’s Wife
-
 Sports4 months ago
The 15 Highest-Paid Rugby Players in the World
-
Celebrity10 months ago
Christopher Dare: The Untold Story of Engineer and Former Husband of Angela Rippon
-
 Real Estate8 months ago
How to Ensure Your Home is Valued Correctly for a Quick Sale
-
 Technology4 months ago
What Is Fanquer? The Digital Creator Platform Transforming Direct-to-Fan Engagement
-
 Celebrity4 months ago
Dr Jared Ross: Missouri Appeals Court Upholds Protection Order Over Graphic Torture and Murder Threats
-
Celebrity11 months ago
Nancy Hallam: The Inspiring Life, Career, and Success Story Behind Ian Wright’s Wife
-
 Health8 months ago
Enclomimed 25 (Enclomiphene) – Effective PCT Protocol
-
 Celebrity10 months ago
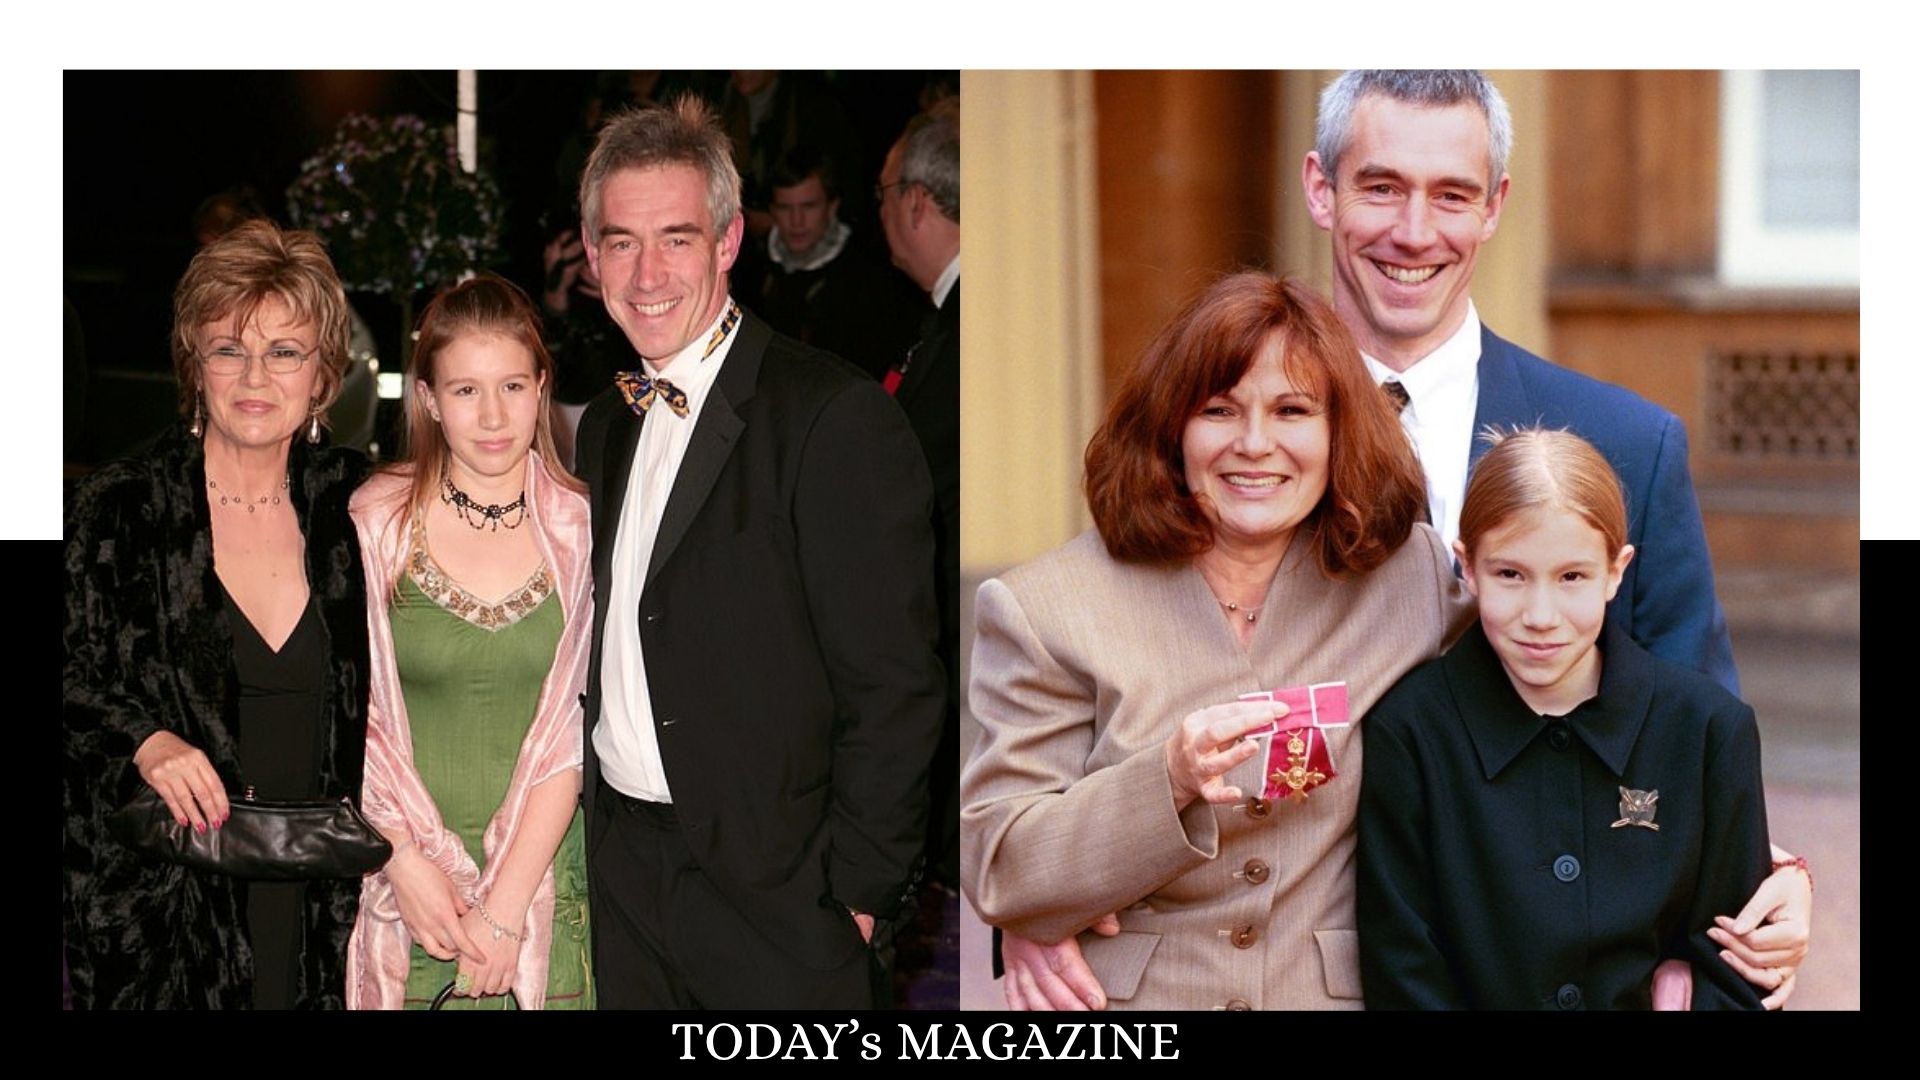
Who Is Maisie Mae Roffey? The Private Life, Family Story, and Quiet Success of Julie Walters’ Daughter