Business
7 Wealth Management Testing Frameworks Every US Financial Advisor Should Know in 2025

Financial advisory practices in the United States are operating under a level of scrutiny that has grown steadily over the past decade. Regulatory expectations have tightened, client profiles have become more complex, and the tools used to manage assets have multiplied. In this environment, the question is no longer whether a firm has a process for managing wealth — it is whether that process has been tested, validated, and stress-examined against conditions that reflect real market behavior and real client circumstances.
Testing in wealth management is not a compliance formality. It is the mechanism by which advisory firms confirm that their strategies, models, and client-facing recommendations hold up when conditions change. In 2025, with interest rate volatility, shifting retirement demographics, and increasing demand for personalized financial planning, the need for structured testing frameworks is practical and pressing. Advisors who understand these frameworks are better positioned to protect client outcomes, manage operational risk, and meet the expectations of regulators and institutional partners alike.
The seven frameworks outlined here represent the approaches most relevant to working advisors and planning professionals in the current US market. They are not theoretical models — they reflect how testing actually functions inside financial planning operations.
1. The Role of Wealth Management Testing in Modern Advisory Practice
Structured wealth management testing refers to the systematic process of validating financial strategies, planning models, and portfolio assumptions before they are applied to client situations. When advisory firms engage with wealth management testing, they are essentially running their assumptions through controlled conditions to identify where those assumptions break down. This matters because even well-constructed financial plans carry embedded risks that are not visible until they are put under pressure.
The value of this testing is not found in confirming what already works. It is found in locating the weak points in a plan before a client encounters them in a real market environment.
Why Testing Has Become a Structural Requirement
For most of the past two decades, wealth management firms could rely on relatively stable growth conditions to carry plans forward even when assumptions were imprecise. That buffer no longer exists in the same way. Higher inflation periods, compressed market cycles, and longer retirement horizons mean that plans built on average-case assumptions are increasingly vulnerable to underperformance in anything other than favorable conditions. Testing frameworks exist to replace assumption-based confidence with evidence-based confidence. This shift is not a preference — it is a structural response to the environment advisors now operate within.
2. Monte Carlo Simulation as a Probabilistic Planning Tool
Monte Carlo simulation applies a large number of randomized variable combinations to a financial plan to produce a range of potential outcomes rather than a single projected result. Instead of saying a retirement plan will succeed if markets return a fixed percentage annually, this method runs the plan through thousands of possible market sequences and measures how often it survives. The output is a probability distribution, not a prediction.
Interpreting Results Without Overstating Certainty
One of the practical risks in using Monte Carlo outputs is the tendency to treat probability scores as guarantees. A plan that shows a high probability of success under simulated conditions still contains assumptions about spending behavior, healthcare costs, and longevity that the simulation may not fully capture. Advisors who understand this limitation use Monte Carlo results as a starting point for deeper conversation with clients — not as a final answer. The framework is most useful when it is paired with scenario-specific follow-up testing rather than used in isolation.
3. Stress Testing Against Historical Market Sequences
Historical sequence testing applies actual market data from specific periods — including market downturns, inflationary surges, and prolonged low-return environments — to evaluate how a client’s plan would have performed during those periods. Unlike Monte Carlo methods, this approach does not randomize inputs. It uses real sequences of events to assess plan resilience.
The Problem of Sequence-of-Returns Risk in Retirement Planning
Sequence-of-returns risk is one of the most significant vulnerabilities in withdrawal-phase financial planning. A client who retires just before a sustained market decline faces a fundamentally different financial outcome than a client who retires during a period of growth, even if both clients have identical average returns over a long horizon. Historical sequence testing reveals this vulnerability directly. By running a plan against the market conditions of the early 2000s, the 2008 financial crisis, or the inflationary period of the 1970s, advisors can identify whether a client’s withdrawal strategy holds under realistic worst-case conditions. This is considerably more useful than testing against an assumed average.
4. Asset Liability Matching Validation
Asset liability matching is a framework used primarily in institutional and high-net-worth planning to ensure that the structure of a client’s assets aligns with the timing and magnitude of their future financial obligations. Testing within this framework means verifying that cash flows from investments can meet projected liabilities at the times those liabilities are expected to arise.
How Misalignment Creates Compounding Risk
When asset durations and liability timelines are misaligned, the consequences are not always immediately apparent. A portfolio that looks adequate in total value may still fail to generate the right cash flows at the right times. This is particularly relevant for clients who have predictable future obligations — funding a business transition, covering a long-term care need, or distributing wealth across multiple beneficiaries on a defined schedule. Testing the match between asset structure and liability timing helps advisors catch potential cash flow shortfalls well before they become crises. The Federal Reserve’s research on duration risk in fixed income portfolios provides useful technical grounding for understanding how duration mismatch compounds under interest rate changes.
5. Tax Efficiency and Drawdown Sequence Testing
Tax efficiency testing in wealth management evaluates the order in which assets are drawn down across different account types — taxable accounts, tax-deferred accounts, and tax-exempt accounts — to determine the combination that minimizes total tax liability over the course of a client’s retirement or wealth transfer period.
When Tax Optimization Frameworks Conflict With Other Plan Objectives
The most effective drawdown sequence from a tax perspective is not always aligned with a client’s other priorities, such as preserving Roth accounts for legacy purposes or maintaining flexibility during early retirement years. Testing this framework means running multiple drawdown scenarios and examining the tradeoffs between tax efficiency, estate goals, and liquidity needs. Without this kind of structured comparison, advisors often default to conventional sequencing rules that may not reflect the specific dynamics of a given client’s account structure or tax situation.
6. Behavioral Stress Testing and Client Risk Tolerance Validation
Behavioral stress testing examines how a financial plan functions when client behavior deviates from the assumptions built into the plan. Most financial plans assume clients will stay invested during downturns, maintain spending discipline during market stress, and follow the advisory recommendations they agreed to during calm market conditions. In practice, this is frequently not what happens.
The Gap Between Stated and Revealed Risk Tolerance
Risk tolerance assessments conducted during calm market periods tend to produce results that overstate a client’s actual willingness to absorb portfolio losses. When markets decline sharply, many clients reveal a lower actual tolerance than their questionnaire responses suggested. Advisors who test their plans against behavioral deviation — modeling what happens if a client moves to cash during a downturn or increases spending during a period of portfolio growth — are working with more realistic inputs. This form of wealth management testing does not require advanced software. It requires advisors to build alternative scenarios that reflect realistic human behavior and then measure the consequences of those deviations on plan outcomes.
7. Withdrawal Sustainability Testing Over Variable Longevity Horizons
Withdrawal sustainability testing evaluates whether a portfolio can support a defined level of spending across a range of longevity scenarios. This framework is particularly important as US life expectancy assumptions continue to shift and as clients increasingly face the possibility of retirement periods lasting three or more decades.
The Compounding Impact of Small Assumption Errors Over Long Horizons
A small error in a spending assumption or a return expectation becomes a large error when compounded over thirty years. Testing withdrawal sustainability requires running plans not just to average life expectancy but well beyond it, often to age ninety or ninety-five, to assess whether the plan remains solvent under extended time horizons. It also means testing the plan at different spending levels to identify the point at which the portfolio begins to deteriorate. Advisors who understand the specific threshold at which a client’s plan becomes financially unsustainable are in a far better position to make proactive adjustments than those who discover the problem only when it is close to materializing.
Closing: Building a Testing Practice That Holds Up Over Time
The frameworks described here are not sequential — they are complementary. A well-functioning advisory practice does not choose one and ignore the others. It applies different frameworks at different stages of a client relationship and at different points in the market cycle. Monte Carlo analysis might be the right tool for initial plan construction. Historical sequence testing becomes more relevant as a client approaches retirement. Behavioral stress testing is most valuable after periods of market turbulence, when clients are more likely to act against their own interests.
What connects all seven frameworks is the underlying principle that financial advice should be validated, not assumed. The operational discipline of testing is what separates plans that are theoretically sound from plans that are practically resilient. In 2025, as the complexity of client financial lives continues to grow and the consequences of planning failures become more visible, advisors who have built systematic testing into their practice will be better positioned — not because they have eliminated uncertainty, but because they have examined it honestly and prepared for it deliberately.
For advisors who have not yet formalized their approach to wealth management testing, the starting point is not technology or methodology. It is the recognition that every untested assumption in a financial plan is a risk that the client is carrying without knowing it. The frameworks exist to change that.


When starting a UK business, registering a company name is usually one of the first things on the list. But there is another name-related decision that many business owners overlook: trade mark registration. This often leads to a simple question:
If my company name is already registered with Companies House, why would I need a trade mark?
The answer is that they protect different things. Companies House deals with company registration and company-name rules, while the UK Intellectual Property Office (IPO) deals with trade marks. Registering a company name does not automatically give you trade mark protection.
Need help registering your UK trade mark? BusinAssist can guide you through the UK trade mark application process, helping you take the next step towards protecting your brand.
Explore Our UK Trade Mark Registration Service and start building a stronger foundation for your business.
What Does Companies House Registration Do?
When you form a limited company, you register its legal name with Companies House.
The name must meet Companies House rules and cannot normally be the same as an existing registered company name. If a name is too similar to another company name, you may also have to change it following a complaint.
This gives your company its legal identity. For example, imagine you register: BrightPath Solutions Ltd. That becomes the official name of your limited company. But this does not automatically mean that you have exclusive trade mark rights over “BrightPath Solutions”.
That is where the difference becomes important.
What Does Trade Mark Registration Do?
A trade mark protects a brand used to distinguish your goods or services from those of other businesses.
It can include things such as:
- Business or product names
- Logos
- Certain sounds
- Colours
- Combinations of these elements
A registered trade mark can give the owner stronger rights to take action against unauthorised use of the mark within the relevant scope of protection.
So while Companies House helps establish your company as a legal entity, a trade mark can help protect the brand customers recognise.
Companies House vs Trade Mark Registration
The easiest way to understand the difference is to look at what each registration is designed to do.
| Companies House Registration | Trade Mark Registration |
| Registers a company | Protects a brand or trade mark |
| Gives the business a legal identity | Helps establish exclusive rights in the registered mark |
| Managed by Companies House | Managed by the UK Intellectual Property Office |
| Focuses on company-name rules | Focuses on goods and services covered by the mark |
| Does not automatically create trade mark rights | Can provide stronger legal protection for the registered brand |
| Mainly relevant to the company’s legal identity | Particularly important for customer-facing brands |
The two systems work separately, so registering one does not replace the other.
Why Company Registration Alone May Not Be Enough
Imagine a startup spends two years building a brand around its company name.
It has:
- A popular website
- Thousands of customers
- Social media followers
- Branded packaging
- Paid advertising
- Positive reviews
The founders may assume the company name is protected because it appears on the Companies House register. But company registration does not automatically give the same rights as a registered trade mark.
The IPO specifically warns that registering a company name does not prevent someone else from using a similar or identical trade mark.
That is why checking trade marks should happen before investing heavily in a new brand.
What If Someone Already Has a Similar Trade Mark?
This is where things can become complicated. A company name may be accepted by Companies House but still create a trade mark problem.
For example, you might find that your preferred company name is available, but another business already has a similar registered trade mark covering related goods or services.
Simply having your company name accepted does not automatically solve that problem. Current Companies House guidance recommends checking the UK IPO trade mark register before choosing a company name.
Does a Trade Mark Replace Company Registration?
No. A trade mark and a company are not alternatives.
You can have:
Company registration + trade mark registration
The company registration gives your business its legal identity, while the trade mark can protect the brand you use in the marketplace. A business might therefore operate as:
ABC Innovations Ltd
while using:
ABC
as its customer-facing brand.
The legal company name and the protected brand do not necessarily have to be identical.
What About a Trading Name?
A limited company can also trade under a different name from its registered company name.
For example:
ABC Innovations Ltd
could operate publicly under a trading name.
But using a trading name does not automatically give it trade mark protection.
If the trading name becomes an important part of the company’s brand, registering it as a trade mark may be worth considering. GOV.UK guidance specifically notes that trading names and brands are not automatically protected.
When Should a New Business Think About a Trade Mark?
There is no need to wait until a company becomes large.
In fact, checking the brand early can make business planning easier.
A sensible process is:
- Choose a potential business name.
- Check Companies House.
- Search the UK trade mark database for similar marks.
- Check relevant domains and social media handles.
- Think about how the business could grow.
- Identify the goods and services the brand will cover.
- Consider trade mark registration if the brand is important to the business.
The IPO recommends checking for similar marks before applying and choosing classes and terms that fit the business’s plans.
What Does a Trade Mark Actually Protect?
Trade mark protection is not unlimited. It relates to the goods and services covered by the registration. For example, registering a brand for one category does not automatically mean that nobody anywhere can use the same word for completely unrelated products.
This is why selecting the relevant classes and terms is an important part of the application. The IPO recommends choosing classes and terms that are relevant to your business plans for the next five years. You can consider Trademark Registration guide by BusinAssist to know all the details about trademark registration.
The Simple Way to Think About It
If you remember only one thing from this article, remember this: Companies House protects your company’s place on the company register. A trade mark protects the brand identity you use in the marketplace.
They solve different problems. For a business that is serious about building a recognisable brand, understanding that difference early can prevent unnecessary complications later.
Build the Company. Then Protect What Customers Recognise.
Registering a company is an important first step, but it is only part of building a business. As the company grows, its name, logo and product identity can become valuable commercial assets. Protecting those assets should therefore be considered alongside company formation rather than after the brand has already become established.
If you are setting up or managing a UK company and need support with the administrative side of your business, BusinAssist can help with services including company formation, confirmation statement filing, identity verification and company closure. Your company name may give your business its legal identity. Your brand is what customers remember.
Nobody sets out to tear their software stack apart after six months. But it happens constantly. A founder grabs a free tool early on because it does one job well enough, and then the team doubles, the sales process completely changes, customers start expecting more, and suddenly that same tool becomes the bottleneck holding everyone back.
Startups don’t grow in straight lines. Software picked when the company was three people won’t hold up once there are fifteen, with proper sales channels, active marketing campaigns, revenue targets to hit and new hires to onboard. So what causes the mismatch, and how do you pick something you won’t need to bin within twelve months?
Your Processes Will Change Faster Than You Think
Early on, process doesn’t exist. Leads trickle in from emails, LinkedIn, referrals and maybe the odd event, and someone tracks everything in a spreadsheet that works fine because one person is doing all the selling.
Things change fast though. A second hire joins, marketing kicks off campaigns, and the spreadsheet can’t tell you who last spoke to a lead or how long deals have gone untouched. So the team grabs a CRM, but they pick one that fits the current workflow instead of what they’ll actually need in a few months when the whole operation looks different.
Most startups move from total disorder to a rough system and then to a proper repeatable playbook within about twelve months. That journey breaks tools. Whatever CRM worked during the messy early days will almost certainly buckle once processes get tighter and the team starts demanding more from it.
Pick for Flexibility, Not Just Features
Founders love a long feature list. It’s natural to compare platforms by counting what they offer and going with the one that ticks the most boxes, but that logic falls apart the moment your workflow changes and the tool can’t bend with it.
What actually matters is flexibility. Can you customise fields, rework pipeline stages, add automations and plug in other tools as your stack grows? Reviews comparing the top CRMs for early stage startups now rate platforms on scaling pain points and exit strategies alongside the usual pricing breakdowns, which tells you how common this problem really is. So before you commit, ask yourself whether you can reshape the tool in six months without having to rebuild everything from scratch.
Check the Exit Before You Enter
Before you put anything into a new platform, check how easy it is to get your data back out. This step gets skipped constantly. Export options, API access, data portability and migration support aren’t exciting things to evaluate during a free trial, but they’ll save you weeks of pain when you eventually need to switch.
Don’t overlook this part. If a platform makes it difficult to pull out contacts, deal history, pipeline data and communication logs, you’re handing your most valuable business information to a vendor that could effectively trap you, and you won’t spot the problem until it’s already too late.
Every Tool Is Temporary
That sounds dramatic. But it’s a much healthier way to think about software when you’re running a startup, and it changes the way you set things up from day one. You’ll keep data cleaner because you know it’ll need exporting eventually. You’ll document workflows properly because someone new will need to understand them when the platform changes. And you’ll stop building your entire operation around one vendor’s quirks, because you’ve accepted that the tool serving you well right now probably won’t be the one serving you well in eighteen months.
Startups that handle transitions well planned for change from the very beginning. They picked platforms with decent APIs and clean export options, they kept their data structured, and when the time came to move, the migration took days instead of months. Getting lucky with your first platform pick is rare. Being ready to move when you outgrow it is something you can actually control.
What This Means for Your Next Software Decision
Cycling through tools in a young company isn’t a sign that someone made a bad call. It happens naturally when a business grows fast and works things out along the way. The founders who waste the most time and money are the ones who either cling to a tool long past the point where it stopped working, or who panic-switch to something new without checking whether it’ll last any longer than the last one did.
Test the export options before you test the features. Push the flexibility during the trial, not after you’ve committed. Ask about migration paths and what happens to your data if you leave. And don’t get attached to any platform just because it works right now, because what your startup needs at three months old will look nothing like what it needs at eighteen, and the only real mistake is being surprised when that day arrives.

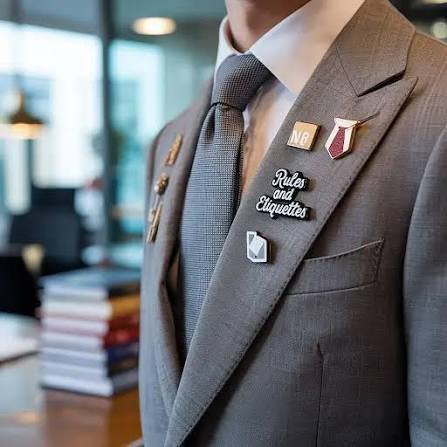
Businesses have to make a lasting impression, and the best way to do it is by increasing their brand visibility through capturing customer interest and developing strong relationships. Branded items are a great way to raise brand awareness, like traditional advertising, social network campaigns, and digital advertising. Corporate pins are among the many options for branding because of their lightweight nature, trendiness, and suitability for branding with logos, colours, and text. This article explains how lapel pins can be used by companies in the UK to promote their business by gifting them, using them in corporate events, and branding employees and clients.
Here are ways businesses use lapel pins to increase visibility of a brand:
For Promotional Gifts
Promotional gifts are an effective tool to introduce a company to potential clients and to keep its products or services in the minds of existing ones. Custom lapel pins are excellent freebies because they are lightweight, portable, and easy to distribute during marketing campaigns. Companies can use branded pins as part of welcome kits, seasonal promotions, purchase incentives, and thank-you packages for customers. Combining lapel pins UK with other promotional products can help a business to design coordinated gift packages that increase their brand awareness.
Employee Branding & Identity
Their interactions with your employees strongly influence your clients’ perception of your company. A clear and professional brand identity throughout the workforce helps customers recognise employees and connect their appearance with the company’s values. Custom lapel pins can be used in corporate attire, uniforms for employees, and name tags. Companies can also use Lapel pins UK to celebrate years of service, distinguish departments, and recognise staff achievements, to keep visual consistency.
Corporate Events & Exhibitions
Exhibitions, trade shows, conferences, and corporate events are some of the best opportunities that companies have to grow their networking with different industry professionals and potential clients. But it’s hard to stand out from the many popular exhibitions. The importance of personalised lapel pins in the UK is very high for companies that want to differ from others with a message through a unique design. You can check out Rocketbadge to get custom-made lapel pins at affordable prices.
Special Edition Products for Special Occasions
Producing special edition products is a great way to raise awareness for the brand and create a sense of intrigue around it. These days, it is quite popular to make custom lapel pins in the UK for many worthy occasions such as milestone events or product launches.
Their uniqueness may be enough to encourage customers, staff, and event-goers to keep them as collectors. Businesses can also encourage customers to post pictures of their limited-edition products on social media to increase the campaign’s reach and visibility online.
Select Designs That Will Help Your Brand
The way promotional lapel pins in the UK are designed has much to do with how well they work. The pin needs to be attractive enough that people will want to wear it, and it needs to clearly identify the company. Businesses should be focusing on recognisable logos, consistent brand colours, clear writing, and appropriate shapes. Simplicity is often more effective, as overcomplicated designs can make it hard to see the finer details.
Conclusion
Lapel pins are a cost-effective and versatile way for companies to market their brand in several ways. They provide companies a chance to connect with the public through everyday connections, collectables, corporate event items, employee accessories, or gifts. Lapel pins in the UK can be an effective part of a bigger promotion plan, as they keep the company in people’s minds long after the end of a campaign when used properly.

The Ultimate Guide to Women’s Sandals for Style and Comfort

Essential Guide to Hire Furniture in Sydney for Stylish Home Makeovers

Publishing AI-Assisted Drafts as PDFs: A Free Markdown Workflow with iBoomto

Spinal Alignment in Kuala Lumpur: What It Involves and What It Costs

When Weeks Turn Into Months: Planning Car Hire for a Longer Stay

Top 10 Best Minicab Companies in London & Surrounding Counties

The 15 Highest-Paid Rugby Players in the World
Christopher Dare: The Untold Story of Engineer and Former Husband of Angela Rippon

How to Ensure Your Home is Valued Correctly for a Quick Sale

What Is Fanquer? The Digital Creator Platform Transforming Direct-to-Fan Engagement

Dr Jared Ross: Missouri Appeals Court Upholds Protection Order Over Graphic Torture and Murder Threats
Nancy Hallam: The Inspiring Life, Career, and Success Story Behind Ian Wright’s Wife
The 15 Highest-Paid Rugby Players in the World
Christopher Dare: The Untold Story of Engineer and Former Husband of Angela Rippon
How to Ensure Your Home is Valued Correctly for a Quick Sale
What Is Fanquer? The Digital Creator Platform Transforming Direct-to-Fan Engagement
Dr Jared Ross: Missouri Appeals Court Upholds Protection Order Over Graphic Torture and Murder Threats
Nancy Hallam: The Inspiring Life, Career, and Success Story Behind Ian Wright’s Wife
-
 Sports5 months ago
The 15 Highest-Paid Rugby Players in the World
-
Celebrity11 months ago
Christopher Dare: The Untold Story of Engineer and Former Husband of Angela Rippon
-
 Real Estate9 months ago
How to Ensure Your Home is Valued Correctly for a Quick Sale
-
 Technology5 months ago
What Is Fanquer? The Digital Creator Platform Transforming Direct-to-Fan Engagement
-
 Celebrity5 months ago
Dr Jared Ross: Missouri Appeals Court Upholds Protection Order Over Graphic Torture and Murder Threats
-
Celebrity11 months ago
Nancy Hallam: The Inspiring Life, Career, and Success Story Behind Ian Wright’s Wife
-
 Celebrity8 months ago
Who Is Azriel Crews? Inside the Life and Career of Terry Crews’ Daughter
-
 Health9 months ago
Enclomimed 25 (Enclomiphene) – Effective PCT Protocol