Business
7 Things Dallas Business Owners Get Wrong When Choosing a Financial Advisor (And How to Fix Them)

Running a business in Dallas comes with a particular kind of financial complexity that most general advisors are not equipped to handle. The decisions a business owner faces — when to reinvest profits, how to structure compensation, what to do with the business itself at exit — are not the same decisions a salaried employee faces. Yet many owners treat the process of finding an advisor the same way they might shop for a bank account: they compare surface-level credentials, ask a few questions, and make a decision based on comfort rather than fit.
The result is often years of misaligned advice. Not bad advice, necessarily — just advice that was designed for someone else’s situation. The problems tend to surface slowly: tax structures that worked fine early on but created complications later, retirement accounts that weren’t optimized around business income cycles, or estate plans that didn’t account for how the business would transfer. By the time these gaps are visible, a significant amount of value has already been lost.
This article outlines seven of the most common mistakes Dallas business owners and executives make when selecting a financial advisor — and what a better approach looks like.
Mistake 1: Treating Business Finances and Personal Finances as Separate Problems
For business owners and executives, personal and business finances are deeply interconnected. The business is often the primary wealth-building vehicle, and decisions made on one side of that line have direct consequences on the other. An advisor who works only on personal investment portfolios without understanding how business cash flow, ownership structure, and exit planning feed into personal wealth is working with incomplete information.
This is one of the core reasons why working with financial advisors in dallas for business owners and executives matters more than simply finding a competent generalist. Advisors who specialize in this audience understand that business income is irregular, that liquidity events require forward planning, and that compensation strategy for an owner is entirely different from W-2 compensation planning.
Why Integration Matters More Than Specialization Alone
It’s not enough for an advisor to simply understand business finances in isolation. What matters is how they connect the business structure to the personal balance sheet. If your business holds significant value but your personal financial plan doesn’t account for how that value will eventually be extracted — whether through sale, transfer, or liquidation — your plan has a fundamental gap. The advisor needs to think about both sides simultaneously, not hand off the personal planning to someone who never speaks with your CPA or attorney.
Mistake 2: Prioritizing Credentials Over Context
Credentials matter, but they don’t tell you whether an advisor has worked with people in situations similar to yours. A CFP designation indicates a standard of knowledge, but it doesn’t mean the advisor has experience with the specific tax and planning challenges that come with owning a closely held business, managing equity compensation, or preparing for a business sale. Context — meaning relevant client experience — often matters more than the letters after someone’s name.
What to Ask Instead of Credential Verification
Rather than spending the first meeting reviewing an advisor’s certifications, ask them to describe the profile of clients they work with most often. Ask them what the most common financial challenges those clients face are. Ask them to explain how they handled a situation where a business owner’s liquidity event changed their entire financial plan on short notice. The answers will tell you far more than a credential audit. An advisor who works primarily with retirees or young professionals is not poorly credentialed — they are simply not the right fit for a business owner with complex equity and tax considerations.
Mistake 3: Choosing an Advisor Based on Social Proof Alone
Referrals from trusted peers are valuable, but they are not sufficient on their own. A business owner might refer a friend to their advisor because the advisor manages their personal portfolio well — without ever mentioning that the friend’s situation includes business ownership, executive compensation, or a pending company sale. The referral is genuine, but the context is missing. When the new client arrives with a different set of needs, the fit may be poor despite the strong recommendation.
The Limits of Peer Recommendations in Professional Services
Financial advice is highly situational. The fact that an advisor performed well for a colleague who has a straightforward investment portfolio does not predict how they will perform for someone whose financial life includes payroll, business debt, commercial real estate, or an eventual exit strategy. Peer recommendations should open the door to a conversation, not close it. The due diligence still needs to happen.
Mistake 4: Underestimating the Role of Tax Coordination
Many business owners treat tax planning and financial planning as two separate services managed by two separate professionals who rarely speak to each other. This creates a coordination gap that costs money over time. Decisions about retirement account contributions, compensation structure, investment timing, and business distributions all carry tax implications. When the financial advisor and the tax professional aren’t working from the same information, those implications often go unaddressed until after the fact.
How Coordination Failures Show Up in Practice
The most common version of this problem appears at tax time, when an owner discovers that a financial decision made earlier in the year created an unexpected tax liability. The advisor made the right call from an investment standpoint; the CPA made the right call from a tax standpoint — but because they weren’t coordinating, the two decisions worked against each other. A qualified advisor working with business owners should either have in-house tax capability or maintain an active working relationship with the client’s CPA throughout the year, not just at year-end.
Mistake 5: Confusing Investment Management With Comprehensive Planning
Investment management — selecting and monitoring a portfolio of assets — is one component of financial planning, not the whole of it. For business owners, the investment portfolio is often not even the most significant financial asset; the business itself typically holds that position. An advisor who focuses almost entirely on managing a portfolio while leaving business valuation, exit planning, insurance strategy, and estate structure to others — or to no one — is not providing comprehensive guidance.
What Comprehensive Planning Actually Covers
Comprehensive financial planning for a business owner typically includes a review of how the business is structured and how that structure affects tax liability, a clear picture of what the business is worth and how that value might change over time, a plan for how personal wealth will be built both during and after the business ownership phase, and coordination across insurance, estate, and tax strategies. According to the CFP Board’s research on financial planning engagement, clients who receive comprehensive planning report significantly better alignment between their financial goals and their actual financial outcomes than those who receive investment management alone. That distinction matters enormously for owners who are building wealth through a business rather than through a paycheck.
Mistake 6: Delaying the Search Until a Major Event Forces It
A large number of business owners don’t engage a financial advisor until something forces the conversation — a sale is imminent, a partner is buying them out, a health event requires succession planning to happen quickly. At that point, the options narrow considerably. Decisions made under time pressure, without an established planning foundation, are almost always less favorable than decisions that were made gradually and deliberately.
The Planning Window That Most Owners Miss
The years between ten and three years before a significant liquidity event are typically when the most meaningful planning work can happen. During that period, business owners can adjust ownership structures, begin separating personal assets from business assets, build out estate plans, and start reducing personal financial dependence on the business. These steps take time to execute properly and require an advisor who already understands the full picture. An advisor brought in six months before a sale can help, but they are largely reacting to a situation rather than shaping it.
Mistake 7: Not Asking How the Advisor Is Compensated
Compensation structure shapes behavior, even when the advisor is acting in good faith. An advisor who earns commissions on the products they recommend faces a different set of incentives than a fee-only advisor who charges based on assets under management or a flat retainer. Neither model is inherently wrong, but owners who don’t understand how their advisor is compensated may not fully understand why certain recommendations are being made.
Why This Question Feels Uncomfortable but Matters Anyway
Most people don’t ask about compensation because it feels like an accusation. It isn’t. It’s a standard question that any qualified advisor should be able to answer clearly and without defensiveness. If an advisor becomes evasive or vague when asked how they are compensated, that response itself is informative. Business owners who are selecting financial advisors in dallas for business owners and executives should ask this question in the first meeting and expect a direct, plain-language answer. The goal isn’t to disqualify advisors who earn commissions — it’s to understand the structure and decide whether it creates any potential conflicts in your specific situation.
Closing Thoughts
The mistakes outlined here are not unusual. They are patterns that show up consistently when business owners treat the advisor selection process as a transaction rather than a structural decision. The right advisor for a business owner is someone who understands the business, works across disciplines, coordinates with other professionals, and maintains a long-term view of how wealth is being built and protected.
Dallas has a large and active market for financial advisors in dallas for business owners and executives, which means there are strong options available — but the volume of choices can make the selection process feel more manageable than it actually is. Having more options doesn’t reduce the importance of asking the right questions. It makes asking them more necessary.
Business owners who approach this decision carefully, who prioritize fit over familiarity and structure over surface-level credentials, tend to end up with advisors who genuinely move the needle. Those who treat it casually often end up repeating the process in a few years — usually after discovering one of the gaps described above. The first approach takes more time upfront. It is consistently the better investment.


When starting a UK business, registering a company name is usually one of the first things on the list. But there is another name-related decision that many business owners overlook: trade mark registration. This often leads to a simple question:
If my company name is already registered with Companies House, why would I need a trade mark?
The answer is that they protect different things. Companies House deals with company registration and company-name rules, while the UK Intellectual Property Office (IPO) deals with trade marks. Registering a company name does not automatically give you trade mark protection.
Need help registering your UK trade mark? BusinAssist can guide you through the UK trade mark application process, helping you take the next step towards protecting your brand.
Explore Our UK Trade Mark Registration Service and start building a stronger foundation for your business.
What Does Companies House Registration Do?
When you form a limited company, you register its legal name with Companies House.
The name must meet Companies House rules and cannot normally be the same as an existing registered company name. If a name is too similar to another company name, you may also have to change it following a complaint.
This gives your company its legal identity. For example, imagine you register: BrightPath Solutions Ltd. That becomes the official name of your limited company. But this does not automatically mean that you have exclusive trade mark rights over “BrightPath Solutions”.
That is where the difference becomes important.
What Does Trade Mark Registration Do?
A trade mark protects a brand used to distinguish your goods or services from those of other businesses.
It can include things such as:
- Business or product names
- Logos
- Certain sounds
- Colours
- Combinations of these elements
A registered trade mark can give the owner stronger rights to take action against unauthorised use of the mark within the relevant scope of protection.
So while Companies House helps establish your company as a legal entity, a trade mark can help protect the brand customers recognise.
Companies House vs Trade Mark Registration
The easiest way to understand the difference is to look at what each registration is designed to do.
| Companies House Registration | Trade Mark Registration |
| Registers a company | Protects a brand or trade mark |
| Gives the business a legal identity | Helps establish exclusive rights in the registered mark |
| Managed by Companies House | Managed by the UK Intellectual Property Office |
| Focuses on company-name rules | Focuses on goods and services covered by the mark |
| Does not automatically create trade mark rights | Can provide stronger legal protection for the registered brand |
| Mainly relevant to the company’s legal identity | Particularly important for customer-facing brands |
The two systems work separately, so registering one does not replace the other.
Why Company Registration Alone May Not Be Enough
Imagine a startup spends two years building a brand around its company name.
It has:
- A popular website
- Thousands of customers
- Social media followers
- Branded packaging
- Paid advertising
- Positive reviews
The founders may assume the company name is protected because it appears on the Companies House register. But company registration does not automatically give the same rights as a registered trade mark.
The IPO specifically warns that registering a company name does not prevent someone else from using a similar or identical trade mark.
That is why checking trade marks should happen before investing heavily in a new brand.
What If Someone Already Has a Similar Trade Mark?
This is where things can become complicated. A company name may be accepted by Companies House but still create a trade mark problem.
For example, you might find that your preferred company name is available, but another business already has a similar registered trade mark covering related goods or services.
Simply having your company name accepted does not automatically solve that problem. Current Companies House guidance recommends checking the UK IPO trade mark register before choosing a company name.
Does a Trade Mark Replace Company Registration?
No. A trade mark and a company are not alternatives.
You can have:
Company registration + trade mark registration
The company registration gives your business its legal identity, while the trade mark can protect the brand you use in the marketplace. A business might therefore operate as:
ABC Innovations Ltd
while using:
ABC
as its customer-facing brand.
The legal company name and the protected brand do not necessarily have to be identical.
What About a Trading Name?
A limited company can also trade under a different name from its registered company name.
For example:
ABC Innovations Ltd
could operate publicly under a trading name.
But using a trading name does not automatically give it trade mark protection.
If the trading name becomes an important part of the company’s brand, registering it as a trade mark may be worth considering. GOV.UK guidance specifically notes that trading names and brands are not automatically protected.
When Should a New Business Think About a Trade Mark?
There is no need to wait until a company becomes large.
In fact, checking the brand early can make business planning easier.
A sensible process is:
- Choose a potential business name.
- Check Companies House.
- Search the UK trade mark database for similar marks.
- Check relevant domains and social media handles.
- Think about how the business could grow.
- Identify the goods and services the brand will cover.
- Consider trade mark registration if the brand is important to the business.
The IPO recommends checking for similar marks before applying and choosing classes and terms that fit the business’s plans.
What Does a Trade Mark Actually Protect?
Trade mark protection is not unlimited. It relates to the goods and services covered by the registration. For example, registering a brand for one category does not automatically mean that nobody anywhere can use the same word for completely unrelated products.
This is why selecting the relevant classes and terms is an important part of the application. The IPO recommends choosing classes and terms that are relevant to your business plans for the next five years. You can consider Trademark Registration guide by BusinAssist to know all the details about trademark registration.
The Simple Way to Think About It
If you remember only one thing from this article, remember this: Companies House protects your company’s place on the company register. A trade mark protects the brand identity you use in the marketplace.
They solve different problems. For a business that is serious about building a recognisable brand, understanding that difference early can prevent unnecessary complications later.
Build the Company. Then Protect What Customers Recognise.
Registering a company is an important first step, but it is only part of building a business. As the company grows, its name, logo and product identity can become valuable commercial assets. Protecting those assets should therefore be considered alongside company formation rather than after the brand has already become established.
If you are setting up or managing a UK company and need support with the administrative side of your business, BusinAssist can help with services including company formation, confirmation statement filing, identity verification and company closure. Your company name may give your business its legal identity. Your brand is what customers remember.
Nobody sets out to tear their software stack apart after six months. But it happens constantly. A founder grabs a free tool early on because it does one job well enough, and then the team doubles, the sales process completely changes, customers start expecting more, and suddenly that same tool becomes the bottleneck holding everyone back.
Startups don’t grow in straight lines. Software picked when the company was three people won’t hold up once there are fifteen, with proper sales channels, active marketing campaigns, revenue targets to hit and new hires to onboard. So what causes the mismatch, and how do you pick something you won’t need to bin within twelve months?
Your Processes Will Change Faster Than You Think
Early on, process doesn’t exist. Leads trickle in from emails, LinkedIn, referrals and maybe the odd event, and someone tracks everything in a spreadsheet that works fine because one person is doing all the selling.
Things change fast though. A second hire joins, marketing kicks off campaigns, and the spreadsheet can’t tell you who last spoke to a lead or how long deals have gone untouched. So the team grabs a CRM, but they pick one that fits the current workflow instead of what they’ll actually need in a few months when the whole operation looks different.
Most startups move from total disorder to a rough system and then to a proper repeatable playbook within about twelve months. That journey breaks tools. Whatever CRM worked during the messy early days will almost certainly buckle once processes get tighter and the team starts demanding more from it.
Pick for Flexibility, Not Just Features
Founders love a long feature list. It’s natural to compare platforms by counting what they offer and going with the one that ticks the most boxes, but that logic falls apart the moment your workflow changes and the tool can’t bend with it.
What actually matters is flexibility. Can you customise fields, rework pipeline stages, add automations and plug in other tools as your stack grows? Reviews comparing the top CRMs for early stage startups now rate platforms on scaling pain points and exit strategies alongside the usual pricing breakdowns, which tells you how common this problem really is. So before you commit, ask yourself whether you can reshape the tool in six months without having to rebuild everything from scratch.
Check the Exit Before You Enter
Before you put anything into a new platform, check how easy it is to get your data back out. This step gets skipped constantly. Export options, API access, data portability and migration support aren’t exciting things to evaluate during a free trial, but they’ll save you weeks of pain when you eventually need to switch.
Don’t overlook this part. If a platform makes it difficult to pull out contacts, deal history, pipeline data and communication logs, you’re handing your most valuable business information to a vendor that could effectively trap you, and you won’t spot the problem until it’s already too late.
Every Tool Is Temporary
That sounds dramatic. But it’s a much healthier way to think about software when you’re running a startup, and it changes the way you set things up from day one. You’ll keep data cleaner because you know it’ll need exporting eventually. You’ll document workflows properly because someone new will need to understand them when the platform changes. And you’ll stop building your entire operation around one vendor’s quirks, because you’ve accepted that the tool serving you well right now probably won’t be the one serving you well in eighteen months.
Startups that handle transitions well planned for change from the very beginning. They picked platforms with decent APIs and clean export options, they kept their data structured, and when the time came to move, the migration took days instead of months. Getting lucky with your first platform pick is rare. Being ready to move when you outgrow it is something you can actually control.
What This Means for Your Next Software Decision
Cycling through tools in a young company isn’t a sign that someone made a bad call. It happens naturally when a business grows fast and works things out along the way. The founders who waste the most time and money are the ones who either cling to a tool long past the point where it stopped working, or who panic-switch to something new without checking whether it’ll last any longer than the last one did.
Test the export options before you test the features. Push the flexibility during the trial, not after you’ve committed. Ask about migration paths and what happens to your data if you leave. And don’t get attached to any platform just because it works right now, because what your startup needs at three months old will look nothing like what it needs at eighteen, and the only real mistake is being surprised when that day arrives.

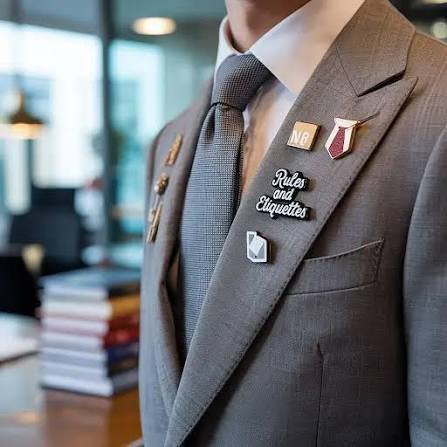
Businesses have to make a lasting impression, and the best way to do it is by increasing their brand visibility through capturing customer interest and developing strong relationships. Branded items are a great way to raise brand awareness, like traditional advertising, social network campaigns, and digital advertising. Corporate pins are among the many options for branding because of their lightweight nature, trendiness, and suitability for branding with logos, colours, and text. This article explains how lapel pins can be used by companies in the UK to promote their business by gifting them, using them in corporate events, and branding employees and clients.
Here are ways businesses use lapel pins to increase visibility of a brand:
For Promotional Gifts
Promotional gifts are an effective tool to introduce a company to potential clients and to keep its products or services in the minds of existing ones. Custom lapel pins are excellent freebies because they are lightweight, portable, and easy to distribute during marketing campaigns. Companies can use branded pins as part of welcome kits, seasonal promotions, purchase incentives, and thank-you packages for customers. Combining lapel pins UK with other promotional products can help a business to design coordinated gift packages that increase their brand awareness.
Employee Branding & Identity
Their interactions with your employees strongly influence your clients’ perception of your company. A clear and professional brand identity throughout the workforce helps customers recognise employees and connect their appearance with the company’s values. Custom lapel pins can be used in corporate attire, uniforms for employees, and name tags. Companies can also use Lapel pins UK to celebrate years of service, distinguish departments, and recognise staff achievements, to keep visual consistency.
Corporate Events & Exhibitions
Exhibitions, trade shows, conferences, and corporate events are some of the best opportunities that companies have to grow their networking with different industry professionals and potential clients. But it’s hard to stand out from the many popular exhibitions. The importance of personalised lapel pins in the UK is very high for companies that want to differ from others with a message through a unique design. You can check out Rocketbadge to get custom-made lapel pins at affordable prices.
Special Edition Products for Special Occasions
Producing special edition products is a great way to raise awareness for the brand and create a sense of intrigue around it. These days, it is quite popular to make custom lapel pins in the UK for many worthy occasions such as milestone events or product launches.
Their uniqueness may be enough to encourage customers, staff, and event-goers to keep them as collectors. Businesses can also encourage customers to post pictures of their limited-edition products on social media to increase the campaign’s reach and visibility online.
Select Designs That Will Help Your Brand
The way promotional lapel pins in the UK are designed has much to do with how well they work. The pin needs to be attractive enough that people will want to wear it, and it needs to clearly identify the company. Businesses should be focusing on recognisable logos, consistent brand colours, clear writing, and appropriate shapes. Simplicity is often more effective, as overcomplicated designs can make it hard to see the finer details.
Conclusion
Lapel pins are a cost-effective and versatile way for companies to market their brand in several ways. They provide companies a chance to connect with the public through everyday connections, collectables, corporate event items, employee accessories, or gifts. Lapel pins in the UK can be an effective part of a bigger promotion plan, as they keep the company in people’s minds long after the end of a campaign when used properly.

The Ultimate Guide to Women’s Sandals for Style and Comfort

Essential Guide to Hire Furniture in Sydney for Stylish Home Makeovers

Publishing AI-Assisted Drafts as PDFs: A Free Markdown Workflow with iBoomto

Spinal Alignment in Kuala Lumpur: What It Involves and What It Costs

When Weeks Turn Into Months: Planning Car Hire for a Longer Stay

Top 10 Best Minicab Companies in London & Surrounding Counties

The 15 Highest-Paid Rugby Players in the World
Christopher Dare: The Untold Story of Engineer and Former Husband of Angela Rippon

How to Ensure Your Home is Valued Correctly for a Quick Sale

What Is Fanquer? The Digital Creator Platform Transforming Direct-to-Fan Engagement

Dr Jared Ross: Missouri Appeals Court Upholds Protection Order Over Graphic Torture and Murder Threats
Nancy Hallam: The Inspiring Life, Career, and Success Story Behind Ian Wright’s Wife
The 15 Highest-Paid Rugby Players in the World
Christopher Dare: The Untold Story of Engineer and Former Husband of Angela Rippon
How to Ensure Your Home is Valued Correctly for a Quick Sale
What Is Fanquer? The Digital Creator Platform Transforming Direct-to-Fan Engagement
Dr Jared Ross: Missouri Appeals Court Upholds Protection Order Over Graphic Torture and Murder Threats
Nancy Hallam: The Inspiring Life, Career, and Success Story Behind Ian Wright’s Wife
-
 Sports5 months ago
The 15 Highest-Paid Rugby Players in the World
-
Celebrity11 months ago
Christopher Dare: The Untold Story of Engineer and Former Husband of Angela Rippon
-
 Real Estate9 months ago
How to Ensure Your Home is Valued Correctly for a Quick Sale
-
 Technology5 months ago
What Is Fanquer? The Digital Creator Platform Transforming Direct-to-Fan Engagement
-
 Celebrity5 months ago
Dr Jared Ross: Missouri Appeals Court Upholds Protection Order Over Graphic Torture and Murder Threats
-
Celebrity11 months ago
Nancy Hallam: The Inspiring Life, Career, and Success Story Behind Ian Wright’s Wife
-
 Celebrity8 months ago
Who Is Azriel Crews? Inside the Life and Career of Terry Crews’ Daughter
-
 Health9 months ago
Enclomimed 25 (Enclomiphene) – Effective PCT Protocol