Blog
Applying for a Personal Loan Directly or Through a Broker: What to Expect

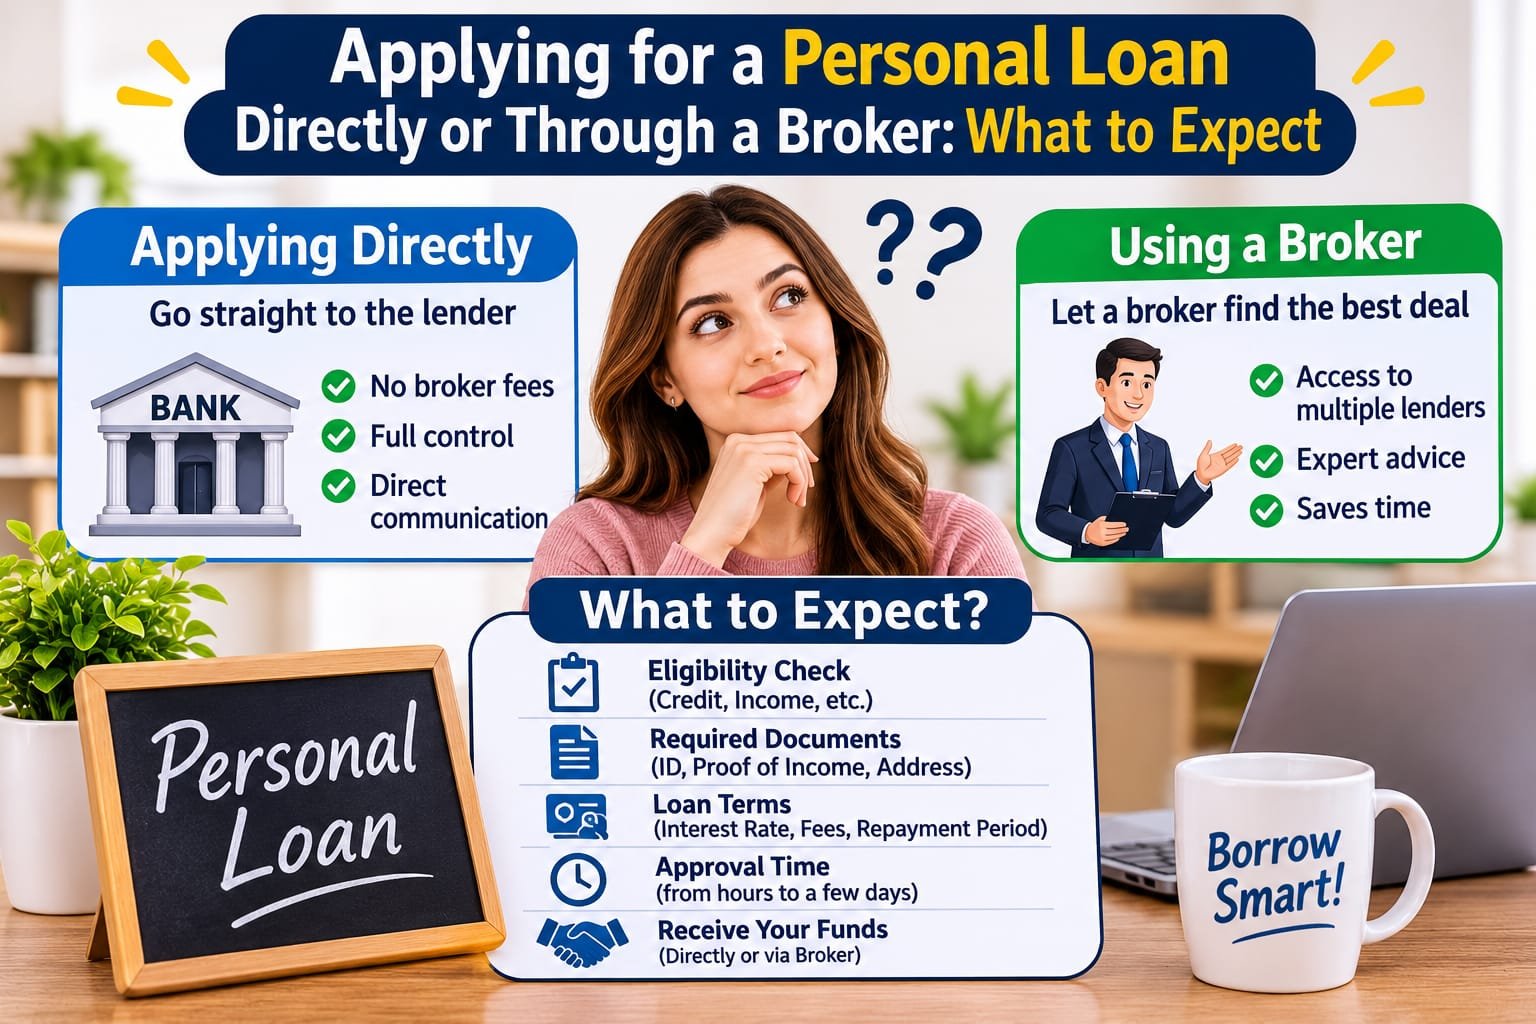
Applying directly and applying through a broker both end at the same place: a lender decision. The difference is who handles the middle steps and who you contact if questions come up. A useful comparison is how each route provides a realistic quote and makes responsibility clear.
What a direct lender handles start to finish
A direct lender considers applications for its own loan products rather than introducing applicants to another lender. Applicants submit details on the lender’s form, and the lender assesses eligibility and affordability before making a decision. The rate and fee structure come from that provider. The agreement and account information identify the contact for later balance questions and any requests about the payment schedule.
Eligibility rules are set lender by lender, so one lender may accept applicants with limited history while another wants longer employment records and steadier income. That variation explains why two direct applications for the same amount can produce different answers. An applicant’s position becomes clearer once that lender has reviewed income, housing costs, current debt, and payment history. The applicant knows which lender is assessing the request. The application page explains how to supply supporting documents, while the provider’s privacy information describes how those details are handled.
Servicing covers statements, balance updates and account questions. The agreement identifies who handles those tasks and which contact channels are available. Applicants can ask whether the originating lender will also service the account. Keeping those details with the agreement provides a clear record for later questions.
That direct line is the main appeal.
What a broker handles and what it doesn’t
A broker doesn’t fund the loan. It takes applicant details and screens that file against lending criteria, then passes it to one or more lenders that might approve it. The final yes or no always sits with the lender, not the broker. An introduction or indicative quote from a broker is therefore a lead-in, not a loan approval. Terms can still change after the lender has completed its own checks.
Most brokers work from a panel rather than every lender in existence. The size of that panel matters, since a panel of four lenders gives a far narrower comparison than a panel of forty. Some brokers focus on mainstream profiles with steady income and clean files, while others focus on applicants with thin files or past missed payments. Neither focus is good or bad on its own. What matters is whether the panel fits the applicant’s situation and whether that fit is stated plainly.
Brokers earn money for their service, and the common model is commission paid by the lender after a funded loan. The amount and timing vary by service, so applicants often ask how a broker is paid and whether that payment affects the range of lenders shown.
What an introduction or quote really means
The word introduction causes a lot of confusion. It simply means the broker has passed applicant details to a lender for that lender to consider. It doesn’t mean funds are reserved or terms are locked. A quote at this stage is usually indicative, based on limited information before full verification.
Lenders refine that early figure after checks on income, housing costs, existing borrowing, and repayment history. The personalized figure can match the indicative figure, but it can also shift if affordability looks tighter than first stated. That’s normal and doesn’t signal an error by either party. Comparison sites add another layer, because many of them act as brokers that earn commission when an introduction turns into a funded loan. Knowing that setup helps applicants understand what headline results represent.
A broker’s description of its market coverage should explain which lenders and products its search includes. A panel-based comparison covers the lenders on that panel, not automatically every available provider. Useful questions include whether the search includes specialist lenders and whether any providers must be approached directly. Specific information about coverage makes the results easier to understand.
What credit searches mean in practice
Credit-file reviews can happen at different application stages. A soft search can support an eligibility check without affecting the credit score. It can appear in the applicant’s own report. A hard search is recorded on the file and can be seen by other lenders. The search record shows that a check took place, not whether an application was approved or declined.
Applicants who feel unsure about approval often want to understand their position before authorizing a full application. Some lenders give an initial eligibility view based on a soft search, allowing applicants to see a conditional decision at that stage. A soft-search direct lender such as Evlo Loans offers that eligibility check before any hard search is recorded. That early view isn’t a final approval, but it gives a clearer sense of likely terms. The applicant then decides whether to proceed to full verification.
Stages vary by service, including when a hard search happens and who runs it. Brokers and lenders don’t necessarily follow the same order.
What affordability checks usually involve
Income verification sits at the center of every decision. Employed applicants are usually asked for recent pay slips and bank statements that show regular deposits. Self-employed applicants often provide a longer trail, such as tax returns plus business bank activity across several months. Housing costs get close attention too, whether that’s rent payments or mortgage payments. Lenders weigh those housing costs alongside current debt and day-to-day outgoings to judge residual income.
The goal is to test whether repayments remain manageable if costs rise or hours dip. Applicants with thin files can still pass when income is stable and outgoings leave clear headroom, while applicants with higher income can still be declined when existing borrowing already stretches the budget. Having recent bank records and proof of address available tends to keep the process organized.
Unsecured borrowing has no collateral backing it, so this review carries real weight. Questions commonly cover employment type, length of service, monthly surplus after bills, and plans for income changes. Short answers backed by documents work better than estimates.
Living arrangements often shape the questions asked. Renters may be asked for tenancy details and proof of regular rent, while applicants living with family may be asked about contributions to household costs. Consistent answers across forms prevent delays during verification.
How to compare quotes on equal terms
Headline numbers rarely tell the full story. The figure that allows fair comparison is the APR, which rolls interest and mandatory fees into a single yearly rate. Monthly repayment alone can mislead, since a lower payment stretched over a longer term can cost more overall. Quotes using the same amount and same term make differences in cost easier to see. Whether fees are included in the balance or added separately also changes the total.
Personalized rates can differ from advertised examples. An advertisement describes an offer using a representative rate and stated assumptions; it is not an individual assessment of the reader. An actual quote reflects the applicant’s details and the lender’s assessment. That distinction helps explain why a personal quote may not match a headline figure. The paperwork also identifies who funds the loan and who services it, alongside the APR and total repayable used to compare options.
A quote’s date matters too, since terms can expire or change after fresh checks. Side-by-side notes make close comparisons easier than relying on memory. This part of the process deserves time.
How contact and follow up work on each route
Contact patterns differ by provider and application stage. With a direct application, the named lender is the starting point for questions about its products. It may use several channels, such as email, phone or an online account. The application information identifies the next steps, while reference numbers help connect later messages to the request.
With a broker, contact may come in two phases. The broker may confirm details and explain next steps, then named lenders from the panel make contact about their own checks and decisions. The number of messages and calls depends on how many lenders review the file and what contact permission was given. Some applicants prefer that relay, since they submit details once instead of filling separate forms for each lender. Others prefer to control contact themselves and approach lenders one by one.
Either way, clear information upfront about who will make contact and how data is stored helps applicants understand the process. A record of names and reference numbers keeps follow-up organized. Clear records prevent repeat requests for the same document.
How to choose a route that fits your situation
Choice often comes down to confidence and circumstance rather than a universal winner. Applicants who already know which lender fits their profile sometimes go direct to keep paperwork in one place. Applicants who feel unsure where they fit sometimes use a broker to test across a panel without retyping details for each lender. Both approaches can work when the applicant understands who runs each check and when each check happens. Headlines alone don’t explain those differences.
A consistent amount and term give every quote the same starting point. Income details, housing costs, current borrowing, and recent statements help keep answers consistent across applications. Other useful points of comparison include how eligibility is assessed and how payment for the service works. The timing of a hard search and the party running it also matter, since stages vary by service.
A conditional view gives applicants information to consider before authorizing a full application. Comparing the APR and total repayable is part of deciding whether further checks feel worthwhile. That pause allows time to consider both the cost and the next stage of the application.
Direct and broker routes both lead to a lender decision, just by different paths. The practical differences concern who funds the loan, who handles contact, and when checks happen. Keeping amount and term constant makes the APR and total repayable easier to compare. Those details leave less room for surprise whichever route is chosen.


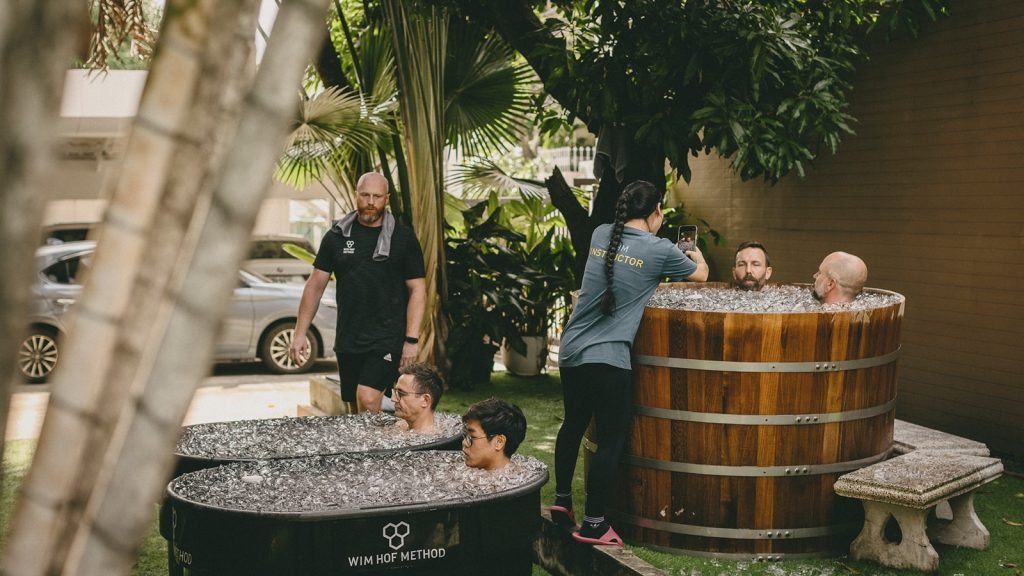
Bangkok has steadily emerged as a prominent global destination for those seeking advanced health and well-being solutions, moving beyond its traditional reputation as a vibrant cultural hub. The city now offers a sophisticated array of services, from invigorating ice baths to comprehensive longevity clinics, catering to a growing demand for holistic recovery and preventive health. This transformation positions Bangkok as a leader in the flourishing field of recovery wellness, attracting individuals worldwide who prioritize their physical and mental restoration.
The synergy of cutting-edge medical technology, skilled practitioners, and a deep-rooted culture of hospitality creates an unparalleled environment for personal rejuvenation. Whether one is an athlete aiming for peak performance, an executive seeking stress relief, or someone simply looking to invest in long-term health, the options for recovery wellness in Bangkok are both diverse and accessible.
We delve into the diverse landscape of recovery and wellness offerings available across the Thai capital, exploring the innovative treatments and serene environments that make Bangkok a top choice for a transformative health journey. Understanding the breadth of services available can help individuals tailor their experience to meet specific health goals.
The rise of recovery wellness in Bangkok
Bangkok’s strategic location in Southeast Asia, combined with its forward-thinking approach to healthcare, has fueled its ascent as a premier destination for recovery and wellness. The city boasts world-class facilities equipped with the latest technologies, often at a value that is highly attractive compared to Western counterparts. This unique combination draws a global clientele seeking high-quality care without compromise.
A blend of tradition and innovation
What sets Bangkok apart in the wellness sphere is its ability to seamlessly integrate time-honored healing practices with modern scientific advancements. Visitors can experience traditional Thai massages and herbal remedies alongside state-of-the-art diagnostic tools and biohacking therapies. This harmonious blend offers a comprehensive approach to well-being, addressing both ancient wisdom and contemporary needs.
The city’s wellness centers often feature tranquil designs that reflect Thai aesthetics, providing a calming backdrop for healing. These spaces are designed to promote relaxation and mental clarity, enhancing the physical benefits of each treatment. The atmosphere itself contributes significantly to the overall recovery process, fostering a sense of peace and detachment from daily stressors.
Accessibility and quality care
Accessibility is another key factor contributing to Bangkok’s popularity. The city is a major international travel hub, making it easy for people from various continents to reach. Once here, navigating the urban landscape to find wellness facilities is straightforward, with many located in convenient and upscale districts.
The quality of care provided in Bangkok’s recovery and wellness centers is consistently high, reflecting the rigorous standards of its medical and hospitality sectors. Practitioners are often internationally trained, bringing a wealth of expertise and a patient-centric approach to their services. This dedication to excellence ensures that visitors receive effective and personalized treatments tailored to their individual requirements.
Advanced recovery therapies: from cold to light
Bangkok’s recovery landscape is rich with advanced therapies designed to accelerate healing, reduce inflammation, and enhance overall physical performance. These treatments are popular among athletes, individuals recovering from injury, and anyone looking to optimize their body’s natural restorative processes. The range of options ensures that specific needs can be met with precision.
The invigorating power of cold therapy
Cold therapy, particularly in the form of ice baths and whole-body cryotherapy, has gained significant traction for its profound benefits on recovery and mental resilience. Immersing the body in extremely cold temperatures triggers a cascade of physiological responses, including reduced muscle soreness, decreased inflammation, and improved circulation. Many facilities in Bangkok offer specialized chambers and tubs for these treatments.
Beyond physical recovery, cold exposure is also celebrated for its ability to boost mood and energy levels. The initial shock gives way to a feeling of exhilaration, making it a popular choice for those seeking a natural uplift. Regular sessions can contribute to better sleep patterns and enhanced stress management, integrating into a broader wellness routine.
Harnessing light for healing
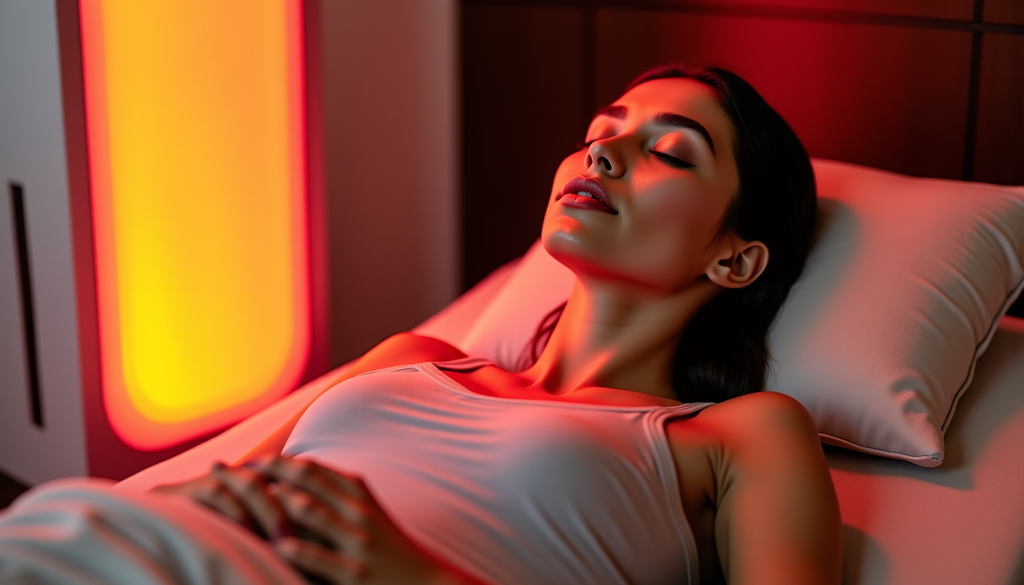
Red light therapy, also known as photobiomodulation, utilizes specific wavelengths of light to stimulate cellular function and promote healing. This non-invasive treatment can help with skin rejuvenation, muscle repair, joint pain relief, and even improve sleep quality. Many wellness centers in Bangkok have integrated advanced red light panels and beds into their offerings.
The gentle, soothing nature of red light therapy makes it a favored option for those seeking effective recovery without intense physical exertion. It works at a cellular level, encouraging the body’s natural regenerative processes. This therapy is particularly beneficial for reducing oxidative stress and enhancing mitochondrial function, which are crucial for overall vitality.
Hyperbaric oxygen therapy for cellular rejuvenation
Hyperbaric oxygen therapy (HBOT) involves breathing pure oxygen in a pressurized chamber, significantly increasing the amount of oxygen dissolved in the blood plasma. This elevated oxygen level can reach areas of the body that are typically oxygen-deprived, promoting tissue repair, reducing swelling, and fighting infections. HBOT is utilized for a wide array of conditions, from wound healing to cognitive enhancement.
In Bangkok, several specialized clinics offer HBOT sessions, often as part of a comprehensive recovery protocol. This therapy is particularly valued for its ability to accelerate recovery from strenuous activity, aid in post-surgical healing, and support neurological health. The controlled environment of the hyperbaric chamber ensures a safe and effective treatment experience.
Longevity clinics: investing in your future self
For those looking beyond immediate recovery and towards long-term health and vitality, Bangkok’s longevity clinics offer sophisticated programs focused on anti-aging and preventive medicine. These clinics adopt a proactive approach, aiming to optimize health spans and enhance quality of life well into later years. They represent a significant investment in future well-being.
Personalized health assessments
A cornerstone of longevity medicine is the comprehensive health assessment. These clinics typically begin with in-depth diagnostic testing, which may include genetic profiling, advanced blood panels, heavy metal analysis, and hormone evaluations. These tests provide a detailed snapshot of an individual’s current health status and potential risk factors, allowing for highly personalized interventions.
The results are then meticulously analyzed by a team of medical professionals, including doctors, nutritionists, and lifestyle coaches. This collaborative approach ensures that every aspect of health is considered, from cellular function to metabolic efficiency. The goal is to uncover root causes of imbalances rather than just treating symptoms, paving the way for targeted strategies.
Tailored anti-aging protocols
Based on the extensive assessments, longevity clinics develop bespoke anti-aging protocols. These may include personalized nutritional plans, targeted supplement recommendations, hormone replacement therapy where appropriate, detoxification programs, and advanced intravenous (IV) therapies. The focus is on optimizing cellular health, boosting energy levels, and mitigating the effects of aging.
Many programs also incorporate lifestyle modifications, encouraging regular physical activity, stress management techniques, and adequate sleep. The journey in a longevity clinic is often ongoing, with regular follow-ups and adjustments to ensure sustained progress. This continuous support empowers individuals to take charge of their health and embrace a vibrant future. To explore a comprehensive guide to these and other wellness offerings, a visit to https://bangkokrecoveryguide.fit/ can provide valuable insights and direct you to suitable facilities.
Holistic approaches to well-being
Beyond the clinical and high-tech interventions, Bangkok also excels in offering a wide range of holistic therapies that nurture the mind, body, and spirit. These approaches are often integrated into wellness retreats and spas, providing a balanced pathway to complete well-being.
Mind-body connection: yoga and meditation
The practice of yoga and meditation is deeply embedded in the wellness culture of Bangkok. Numerous studios and centers offer classes ranging from dynamic Vinyasa flows to serene Hatha sessions, catering to all levels of experience. These practices are invaluable for improving flexibility, strength, and mental clarity.
Meditation retreats, often held in peaceful urban sanctuaries or just outside the bustling city, provide opportunities for deep introspection and stress reduction. Learning to quiet the mind and cultivate mindfulness can have profound positive impacts on emotional regulation and overall peace of mind. Many find these practices to be a vital component of their recovery journey.
Nutritional guidance and detox programs
Understanding the critical role of nutrition in health, many wellness centers in Bangkok offer expert nutritional counseling and tailored detox programs. These programs are designed to cleanse the body of toxins, reset metabolic functions, and educate individuals on sustainable healthy eating habits. They can be particularly beneficial for weight management, digestive health, and boosting energy.
The emphasis is often on fresh, locally sourced ingredients, with many programs incorporating plant-based meals and nutrient-dense juices. Participants learn how to make informed food choices that support their long-term health goals, moving beyond temporary fixes to lasting dietary changes. This focus on internal nourishment complements external recovery treatments.
Traditional Thai therapies
No discussion of wellness in Bangkok would be complete without highlighting its rich tradition of Thai therapies. Traditional Thai massage, known for its therapeutic stretching and pressure point techniques, can alleviate muscle tension, improve circulation, and promote deep relaxation. Herbal compresses and steam baths are also widely available, utilizing local herbs for their healing properties.
These ancient practices are not merely about physical relief; they embody a philosophy of balancing the body’s energy lines and promoting a harmonious flow of vital energy. Experienced practitioners use their knowledge to address individual imbalances, offering a truly personalized and culturally rich healing experience. The blend of techniques can leave one feeling both invigorated and profoundly calm.
Navigating your recovery and wellness journey
Embarking on a recovery and wellness journey in Bangkok can be an enriching experience, but it requires some planning to ensure you choose the best options for your needs. The city offers a vast array of facilities, each with its own specialties and atmosphere. Making an informed decision is key to maximizing your benefits.
Choosing the right facility
When selecting a wellness center or clinic, consider several factors. Research their specializations: are you looking for advanced medical diagnostics, intense physical recovery, or a more holistic retreat experience? Reading reviews and looking at testimonials can offer valuable insights into the quality of care and patient satisfaction. We recommend prioritizing facilities with transparent information about their practitioners’ qualifications and the technologies they employ.
Location might also play a role; some prefer the serene environment of a suburban retreat, while others appreciate the convenience of an urban clinic. It is also beneficial to consider whether the facility offers integrated programs that combine multiple therapies, which can be more effective for comprehensive wellness goals.
“The true essence of wellness lies not just in treating ailments, but in cultivating an environment where the body’s innate capacity for healing and thriving is fully supported and encouraged.” – A leading wellness practitioner in Bangkok.
Understanding pricing and packages
The price of recovery wellness in Bangkok varies significantly depending on the type of treatment, the duration, and the exclusivity of the facility. While generally more affordable than in many Western countries, high-end clinics and extensive longevity programs can still represent a substantial investment. Many centers offer package deals that combine several treatments, often at a reduced overall cost.
Here’s a general overview of pricing considerations:
| Service Category | Typical Offerings | Price Range (Indicative) |
| Basic Recovery Therapies | Ice baths, red light therapy (single sessions) | $$ |
| Advanced Recovery Treatments | Cryotherapy, HBOT, IV drips (per session/package) | $$$ |
| Holistic Wellness Programs | Yoga, meditation, traditional Thai massage (sessions/retreats) | to$ |
| Longevity Clinic Consultations | Initial health assessments, basic diagnostics | $to$$ |
| Comprehensive Longevity Programs | Personalized protocols, ongoing support, advanced diagnostics | $$$$$ |
Note: “
“indicatesmoreaccessiblepricing,while”
$$$” represents premium or extensive programs. Actual costs will vary by provider.
It is always advisable to inquire about detailed pricing, what is included in packages, and any potential hidden costs before committing to a program. Many facilities offer initial consultations that can help clarify these aspects and allow you to discuss your budget and expectations.
Frequently asked questions about recovery wellness in Bangkok
We’ve compiled answers to some common questions to further assist you in planning your recovery and wellness journey in Bangkok.
- Is Bangkok safe for medical tourism and wellness travel?
Yes, Bangkok is widely regarded as a safe destination for medical and wellness tourism. The city has a well-developed infrastructure, and reputable clinics adhere to international safety standards. - Do I need a visa to access wellness services in Bangkok?
Visa requirements depend on your nationality. Many countries have visa-on-arrival or visa-free entry agreements for short stays. It’s best to check the latest visa policies with the Royal Thai Embassy or Consulate in your country before traveling. - Are the practitioners in Bangkok’s wellness centers qualified?
Absolutely. Many practitioners in Bangkok’s top wellness centers and longevity clinics hold international certifications and have extensive experience. It’s always a good practice to verify the qualifications of specific practitioners if you have particular concerns. - Can I combine a wellness trip with a regular tourist vacation?
Certainly! Bangkok offers a wealth of cultural attractions, culinary experiences, and shopping opportunities. Many visitors choose to integrate their wellness treatments with exploring the city and its surroundings, creating a balanced and fulfilling trip. - Is language a barrier in Bangkok’s wellness facilities?
Most high-end wellness centers and clinics in Bangkok employ staff who are proficient in English and often other international languages. Communication is generally not an issue, especially in facilities catering to international clients.
Embracing your wellness journey in Bangkok
Bangkok has truly solidified its position as a world-class hub for recovery and wellness, offering an impressive spectrum of services that cater to every aspect of health. From the cutting-edge science of longevity clinics and advanced recovery therapies like cryotherapy and hyperbaric oxygen, to the profound tranquility of traditional Thai healing and mindful practices, the city provides a holistic ecosystem for well-being.
The emphasis on personalized care, combined with a commitment to integrating modern innovations with ancient wisdom, ensures that visitors can find solutions tailored precisely to their individual goals. Whether seeking to optimize physical performance, mitigate the effects of aging, or simply find a peaceful sanctuary for rejuvenation, the opportunities for recovery wellness in Bangkok are expansive and deeply rewarding. Embracing these offerings can lead to a more vibrant, resilient, and balanced life.

Sash windows have a way of turning a modest home improvement plan into a much bigger project. You set out to replace a couple of draughty frames, and somewhere along the way the budget has doubled, the timeline has stretched and you are wondering where it all went wrong.
The good news is that most overspending on sash windows comes down to a handful of avoidable mistakes. Spot them early, and a sash window cost calculator can then help you build a sensible plan rather than a hopeful guess. Here are the seven most common slip-ups, and what to do instead.
1. Treating the First Number You See as the Final Price
It is tempting to latch onto the first figure you come across, whether it is from an advert, a friend or an online sash window cost calculator, and treat it as the price you will pay. Estimates are useful, but they are only a guide.
The final cost depends on the exact size of your openings, the specification you choose, the condition of your existing frames and the installer you use. A figure that looks perfect on screen can change once someone has actually inspected the job.
What to do instead: Use early estimates to set a realistic range, not a fixed number. Then confirm it with detailed written quotes after a site visit.
2. Forgetting About Hidden Repairs
This is probably the most common cause of budget blow-outs, especially in older homes. Once the old windows come out, problems that were hidden for decades can appear: rotten sills, damaged lintels, crumbling plaster, or openings that are out of square.
None of these are unusual in a Victorian or Georgian property, but they all cost money to put right, and they are rarely included in an initial estimate.
What to do instead: Build a contingency into your budget. Setting aside around 10 to 15 per cent for the unexpected is a sensible habit, and if nothing goes wrong, you have money left over for something else.
3. Comparing Quotes That Are Not Like for Like
Three quotes arrive. One is much cheaper than the others, so you go with it. Months later, you discover it excluded the removal of old windows, the making good of plaster and any decorating. Suddenly the bargain does not look so good.
Quotes can differ in material, glazing, hardware, finish, guarantees and what is included in the price. Unless you check each one carefully, you may be comparing very different products and services.
What to do instead: Ask every supplier to quote against the same written specification. Check line by line what is included, and whether the price is supply only or supply and fit.
4. Choosing on Price Alone
The cheapest option is not always the best value, and with sash windows, it can be a false economy. Poorly made sashes can stick, rattle, leak air and wear out sooner than they should. Poor installation can undo even the best product.
It is not about always paying the most. It is about understanding what your money buys, including the quality of materials, the manufacturing standards, the warranty and the installer’s track record.
What to do instead: Look at the whole package. Ask about guarantees, check reviews and, where possible, see examples of previous work. Consider the cost over the life of the windows, not just on day one.
5. Ignoring Planning Rules and Heritage Restrictions
If your property is listed or sits within a conservation area, the choices available to you may be limited. Replacing traditional timber sashes with a different material or design without consent can lead to enforcement action and the expensive job of putting things back as they were.
Even in homes without those restrictions, some local authorities have specific guidelines, so it is worth checking before you commit.
What to do instead: Check with your local planning authority before you finalise your design or place an order. If consent is required, factor the cost and time into your plan.
6. Overlooking the Cost of Upgrades and Extras
A basic specification looks affordable. Then you start adding things: better glazing, a special colour, upgraded locks, trickle vents, slimline panes. Each item seems small, but together they can raise the price significantly.
Some extras are well worth having, such as improved security or better insulation. Others are nice to have rather than essential.
What to do instead: Decide in advance which upgrades are must-haves and which are optional. If you use a sash window cost calculator, add extras one at a time and watch how each one changes the total. That makes it easier to see where your money is going.
7. Skipping the Survey and Measurements
Sash windows are made to measure. If the measurements are wrong, the windows will not fit, and remaking them is expensive. Relying on rough measurements or a hurried estimate is a risky shortcut.
This applies to the quoting stage too. A quick guess at the size can produce a price that is wildly different from the real one.
What to do instead: Measure carefully, more than once, and at several points across each opening. Better still, have the installer carry out a professional survey before anything is manufactured. Many modern tools use photos and AI to produce a first estimate, but a final check by a person remains important.
A Simple Budgeting Checklist
Before you commit, run through these questions:
- Have I set a realistic range rather than a single number?
- Have I included a contingency for hidden repairs?
- Are all my quotes based on the same specification?
- Do I know what is included and excluded in each price?
- Have I checked planning and heritage rules?
- Have I decided which upgrades matter and which do not?
- Have the measurements been properly checked?
If you can answer yes to all seven, you are in a far stronger position than most.
Final Thoughts
Budgeting for sash windows is less about finding the lowest number and more about avoiding the surprises that push costs up. Treat early estimates from a sash window cost calculator as guides, expect the unexpected, compare quotes properly and take the time to get your measurements right.
A little preparation now saves a lot of stress and money later. And once the new windows are in, sliding smoothly and keeping the draughts out, you will be glad you took the care.
A business turnaround can stall even when directors recognize the problem and want to act. Inaccurate forecasts, slow collections, and poorly timed spending can leave a recovery plan short of cash. Recognizing those mistakes gives directors and their advisers a more useful starting point.
Mistaking profit for cash in hand
Under accrual accounting, a profit and loss statement recognizes revenue when it is earned, which may be before payment arrives. Costs are matched and spread in ways that make sense for accounting but don’t match bank movements. A business can look profitable on paper while the bank balance falls each Friday. That falling balance deserves attention even when the accounts show a profit.
Earnings figures can add to the confusion. A positive result still doesn’t show debt repayments or the timing of large supplier payments. It doesn’t show deposits tied up with suppliers or refunds that haven’t cleared. Directors see a margin and assume there’s room to spend when there isn’t.
Profit and cash in hand answer separate questions, and both need attention. Survival depends on what clears on specific dates. Directors often ask a qualified adviser what the cash view shows next to the monthly numbers, and whether expected profit lines up with actual receipts in the bank over the next few weeks.
Cash timing gaps catch even careful teams. A large job can show a healthy margin while labor and materials were paid weeks before the customer pays. A quiet month can still drain cash because rent and loan payments don’t pause. That mismatch is normal in any business with credit terms. It turns risky when spending is approved on profit alone.
A simple habit helps. Reviewing major decisions against bank dates as well as margin gives directors a clearer view of affordability. If the answer isn’t clear, that is a question to raise with qualified advisers before commitments are made.
Running the turnaround off a static budget
Many businesses in distress still steer by an annual budget set months earlier. That budget assumed steady sales and even costs, with no allowance for late receipts or a lost order. By the third month, it no longer describes reality.
A turnaround needs a shorter lens. A rolling 13-week cash flow forecast maps receipts and required payments week by week and rolls forward as each week passes, so directors always see thirteen weeks ahead instead of watching a budget age. It shows which week goes negative if a large receipt slips by seven days. That view supports clearer talks with suppliers and staff.
The model only works if the inputs are current. Management accounts that arrive six weeks late can’t support weekly decisions, while unreconciled bank feeds hide the true starting point. Directors often ask a qualified adviser whether bookkeeping is fast and clean enough to support a weekly view, and what must change so the forecast stays current.
Discipline matters more than detail. A short forecast updated each Friday beats a detailed model that no one revisits. Clear ownership of the update and written assumptions make it easier to keep the figures current and test what has changed.
Without that routine, directors have little reliable information to guide the next decision.
Assuming customers will pay on time
Turnaround plans often assume invoices will be paid on the due date. Reality rarely cooperates. Customers stretch terms when their own cash is tight, and a few slow payers can move the whole forecast by weeks. Hope isn’t a collection method.
The mistake shows up in quiet ways. Forecasts record the full invoice value on the due date with no allowance for delay or dispute. Expected deposits and old balances are treated as money that will arrive soon, even when payment remains uncertain. Each small optimism adds up to a large gap.
Behavior patterns matter more than terms on paper. A customer who usually pays in fifty days won’t suddenly pay in thirty because the business needs cash. A new customer with no payment history carries different uncertainty from a reliable repeat buyer. Directors often ask a qualified adviser how to weight receipts by past behavior rather than by contract date, and what buffer makes sense for large balances.
One approach is to split expected receipts into confirmed and uncertain payments. Confirmed means agreed dates or direct debits. Uncertain means everything else. That split keeps discussions grounded in payment expectations and stops the forecast from drifting.
A forecast can also show what happens if the two largest receipts arrive a week late. If that test breaks payroll, it highlights the need to discuss a larger buffer or faster collection with an adviser before further commitments.
Letting receivables drift while cash runs short
When cash is tight, debtor days tend to rise. Credit checks get skipped for new work, statements go out late, and awkward payment calls get pushed back. Each delay pushes recovery further away.
Tightening this area is often the fastest way to release cash without new borrowing. Clear terms at the start prevent later debate, while regular statements keep balances visible. Prompt calls on overdue amounts show that payment matters. Small businesses sometimes worry that chasing will harm relationships, but silence harms cash more.
Internal teams can find it hard to press long-standing customers. A discussion with business rescue specialists such as McTear Williams & Wood can help directors put collection issues and forecast assumptions in the context of a wider recovery plan.
Resetting the basics helps. Directors can ask a qualified adviser whether credit limits and stop rules fit current risk, and how to reset terms without losing sound work. Clear rules help staff act early and give customers a consistent message.
Locking cash in stock and equipment
Stock and equipment quietly tie up cash that a turnaround needs. Shelves fill with slow lines that may sell one day, while deposits go toward machines that won’t earn for months. Cash sits still while bills keep coming. Stock doesn’t pay wages.
The trap is easy to miss because purchases feel productive. Buying in bulk looks cheaper per unit, and new equipment looks like progress. But each purchase pulls cash forward and pushes the return into the future. When cash is short, that timing hurts.
A clear review helps. A list of stock on hand gives directors and advisers a starting point for examining how fast each line truly moves. Possible responses include marking down slow lines or returning them where terms allow, alongside reorders that reflect near-term sales. That exercise often releases more cash than expected and sharpens buying habits.
Capital spending needs the same test. Directors often ask a qualified adviser whether a planned purchase can wait until cash stabilizes, and what rental or repair choice bridges the gap. If the return sits months away, the scope for delay is worth discussing with advisers before funds are committed.
Working capital connects these decisions. When receivables and stock move faster, cash returns faster. When they stall, even sound sales can’t fund recovery. That link is why turnaround advisers start with the operating cycle before talks turn to funding.
Chasing sales growth the business can’t fund
Growth can drain cash faster than decline. Each new order needs materials and labor before the customer pays. If terms allow sixty days to pay, the business funds two months of cost up front. More orders mean a larger gap, so rising sales can put immediate pressure on cash.
This pattern is often called overtrading. Sales rise and margins look fair, yet the bank falls because working capital can’t carry the load. Directors feel pressure to say yes to every order. Saying yes without funding can make recovery harder.
Pricing and timing can turn ambition into a cash problem. Discounts that win volume but stretch payment terms look good on the sales line and bad in the bank. Large jobs that need upfront spending without deposits create the same strain. The ability to fund delivery matters as much as the value of the order.
Modeling helps. Directors can ask a qualified adviser what the cash cost of growth looks like for each type of sale, and how deposits or staged payments change the picture. That test shows which work helps recovery and which work delays it.
Discipline on order selection pays. Turning down or rescheduling one draining job can protect payroll for the rest. That choice is hard in the moment, but it can be easier than finding emergency cash later when options are thin.
Starting a cash plan and then not tracking it
Many businesses start a cash plan with care and then let it slide. The first forecast looks tidy. Week two brings urgent jobs and the update slips; by week four, no one trusts the numbers. A plan that isn’t tracked can’t guide decisions.
Follow-through means assigning clear ownership. One person updates actuals against forecast each week and explains differences in plain terms. Those differences inform actions for the next seven days. That loop keeps the plan useful and stops small gaps from growing.
Management reporting supports the loop. Monthly numbers that are late or tangled can’t explain variances. Clean sales and cost records show where cash went. Directors often ask a qualified adviser what a simple weekly pack should show, and how to keep it short enough that it actually gets used each Friday.
Behavior is the rest. Teams need to know that cash targets matter as much as sales targets. Leaving supplier calls until the day before payment limits the time available for discussion, while customer promises without dates offer little certainty. When leaders review cash each week without fail, others treat it the same way.
Small slips compound. Catching a shortfall a week early leaves time to discuss adjustments to terms or spending. Catching it a month late leaves few choices and forces rushed calls. Steady tracking is what keeps a turnaround plan honest.
Turnarounds rarely hinge on one large decision. They depend on steady cash habits repeated each week. Businesses that test profit against bank dates and track the plan give recovery a chance to work.

The Latest Women’s Fashion Trends to Shop at SHEIN

What is Brand Identity? Complete Guide for Beginners

Recovery and wellness in Bangkok: from ice baths to longevity clinics

Boiler Servicing in London: Why Skipping It Could Cost You Thousands

7 Costly Mistakes to Avoid When Budgeting for Sash Windows

Common Cash Flow Mistakes That Make Business Turnarounds Harder

How to Ensure Your Home is Valued Correctly for a Quick Sale
Christopher Dare: The Untold Story of Engineer and Former Husband of Angela Rippon

The 15 Highest-Paid Rugby Players in the World

What Is Fanquer? The Digital Creator Platform Transforming Direct-to-Fan Engagement

Dr Jared Ross: Missouri Appeals Court Upholds Protection Order Over Graphic Torture and Murder Threats

Who Is Azriel Crews? Inside the Life and Career of Terry Crews’ Daughter
How to Ensure Your Home is Valued Correctly for a Quick Sale
Christopher Dare: The Untold Story of Engineer and Former Husband of Angela Rippon
The 15 Highest-Paid Rugby Players in the World
What Is Fanquer? The Digital Creator Platform Transforming Direct-to-Fan Engagement
Dr Jared Ross: Missouri Appeals Court Upholds Protection Order Over Graphic Torture and Murder Threats
Who Is Azriel Crews? Inside the Life and Career of Terry Crews’ Daughter
-
 Real Estate10 months ago
How to Ensure Your Home is Valued Correctly for a Quick Sale
-
Celebrity12 months ago
Christopher Dare: The Untold Story of Engineer and Former Husband of Angela Rippon
-
 Sports6 months ago
The 15 Highest-Paid Rugby Players in the World
-
 Technology6 months ago
What Is Fanquer? The Digital Creator Platform Transforming Direct-to-Fan Engagement
-
 Celebrity6 months ago
Dr Jared Ross: Missouri Appeals Court Upholds Protection Order Over Graphic Torture and Murder Threats
-
 Celebrity9 months ago
Who Is Azriel Crews? Inside the Life and Career of Terry Crews’ Daughter
-
 Celebrity1 year ago
Nancy Hallam: The Inspiring Life, Career, and Success Story Behind Ian Wright’s Wife
-
 Celebrity1 year ago
Who Is Maisie Mae Roffey? The Private Life, Family Story, and Quiet Success of Julie Walters’ Daughter